 Money Facts To Know
$60,000 salary, paid monthly: $382.50 goes to Social Security and Medicare
Gross pay isn't take-home pay
$60,000 ÷ 12 is $5,000 a month, before anything is withheld. Our fictional single filer is paid monthly in tax year 2026, with no other income.
Source: Fictional example; tax year 2026
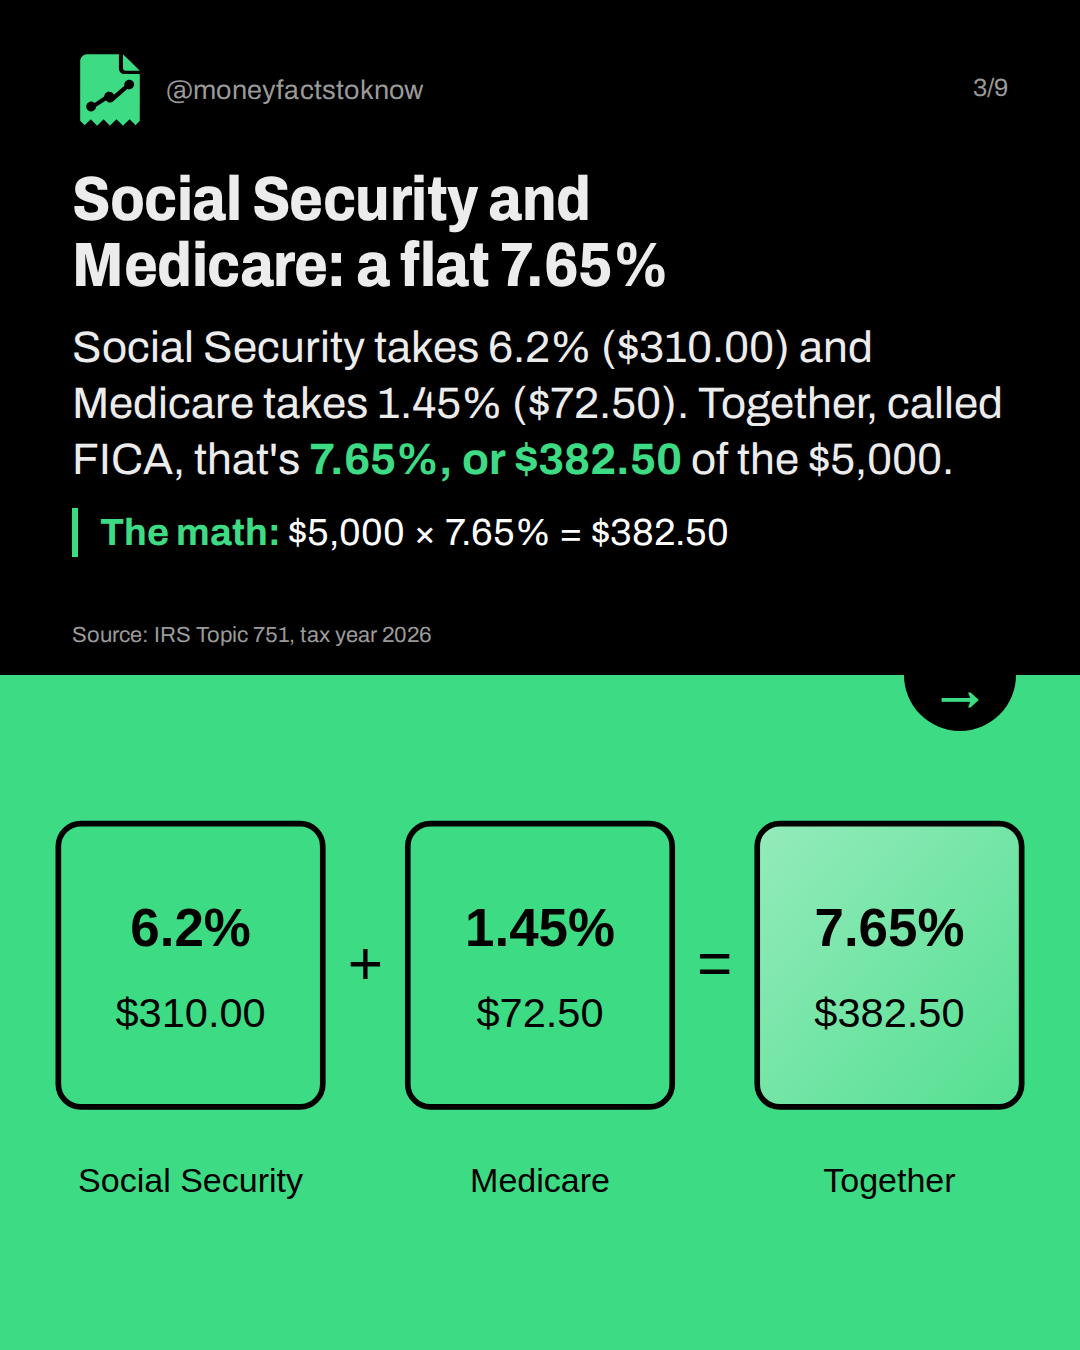
Social Security and Medicare: a flat 7.65%
Social Security takes 6.2% ($310.00) and Medicare takes 1.45% ($72.50). Together, called FICA, that's 7.65%, or $382.50 of the $5,000.
The math: $5,000 × 7.65% = $382.50
Source: IRS Topic 751, tax year 2026
Income tax withholding, figured separately
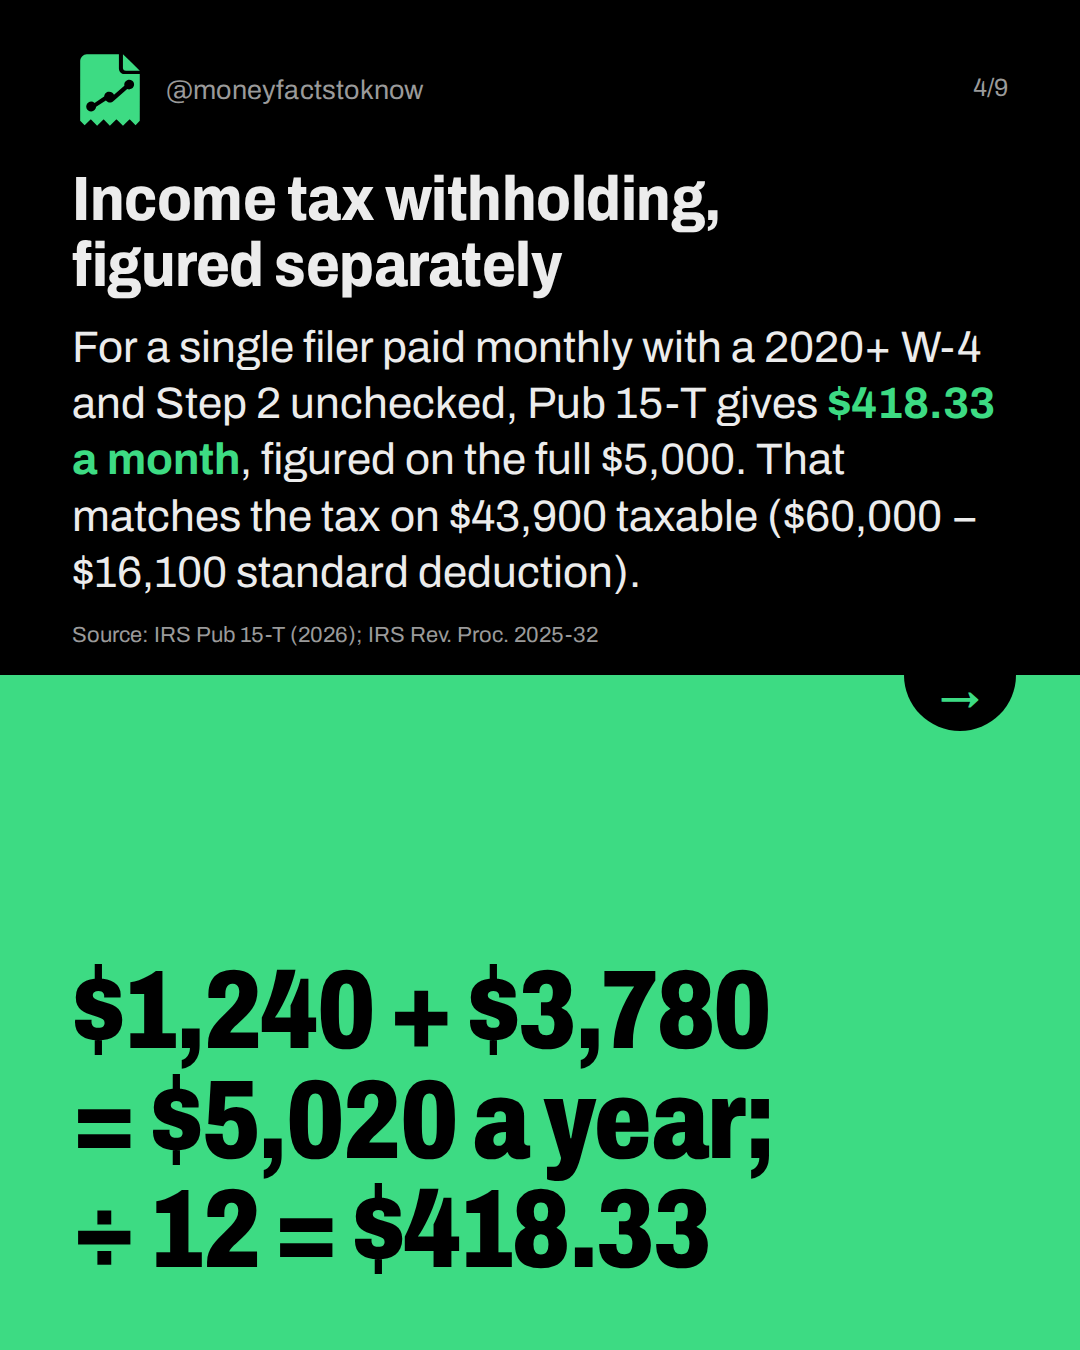
For a single filer paid monthly with a 2020+ W-4 and Step 2 unchecked, Pub 15-T gives $418.33 a month, figured on the full $5,000. That matches the tax on $43,900 taxable ($60,000 − $16,100 standard deduction).
The math: $1,240 + $3,780 = $5,020 a year; ÷ 12 = $418.33
Source: IRS Pub 15-T (2026); IRS Rev. Proc. 2025-32
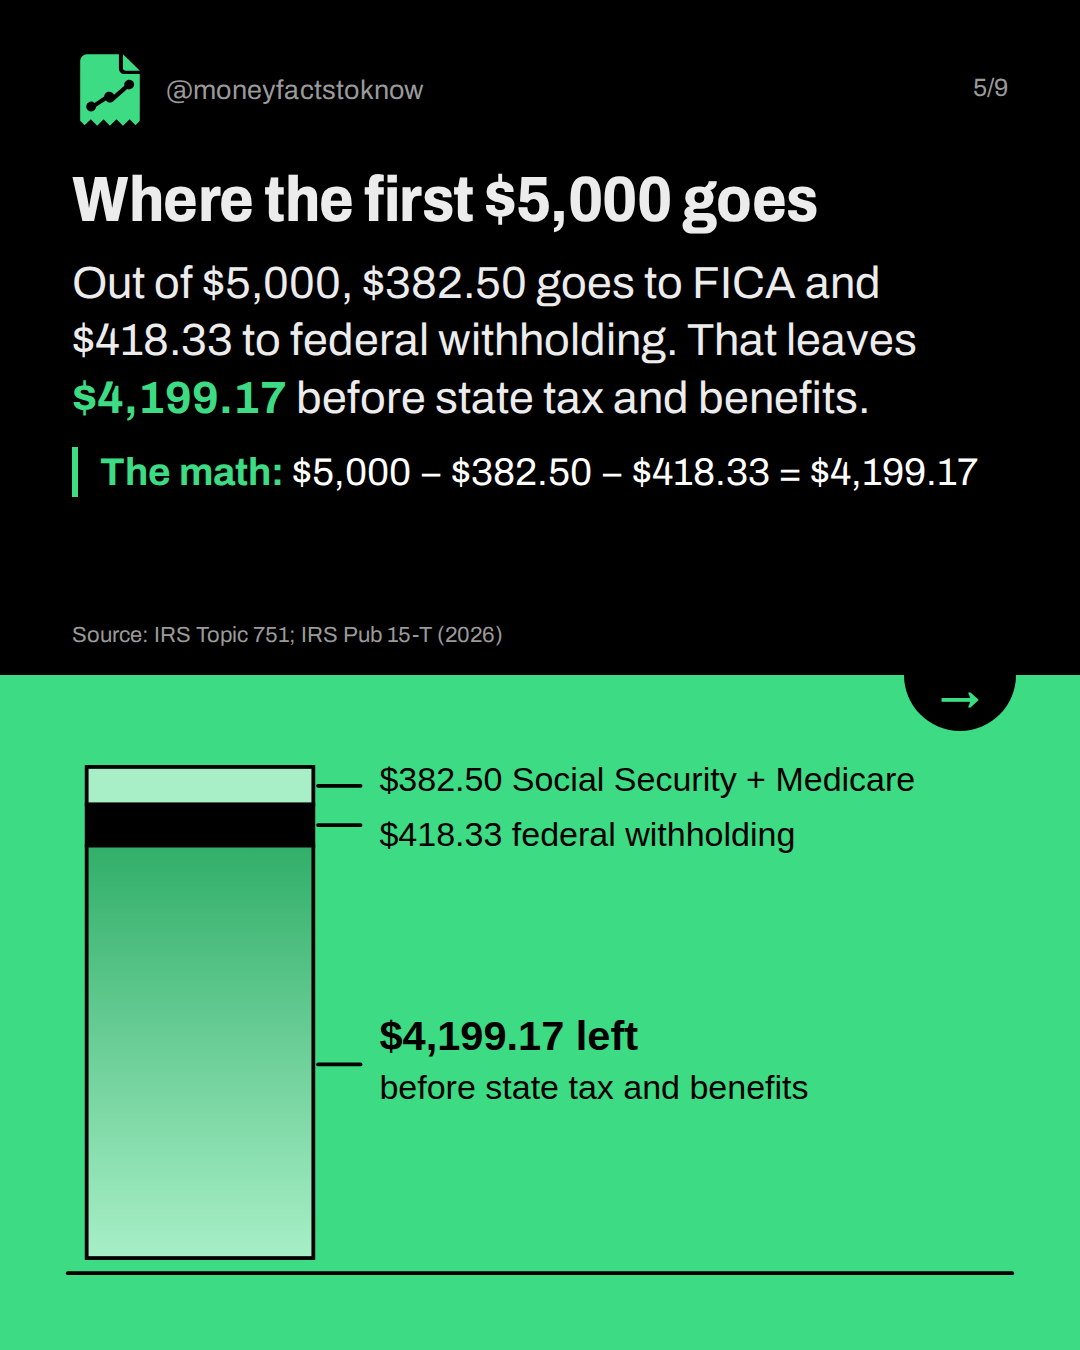
Where the first $5,000 goes
Out of $5,000, $382.50 goes to FICA and $418.33 to federal withholding. That leaves $4,199.17 before state tax and benefits.
The math: $5,000 − $382.50 − $418.33 = $4,199.17
Source: IRS Topic 751; IRS Pub 15-T (2026)
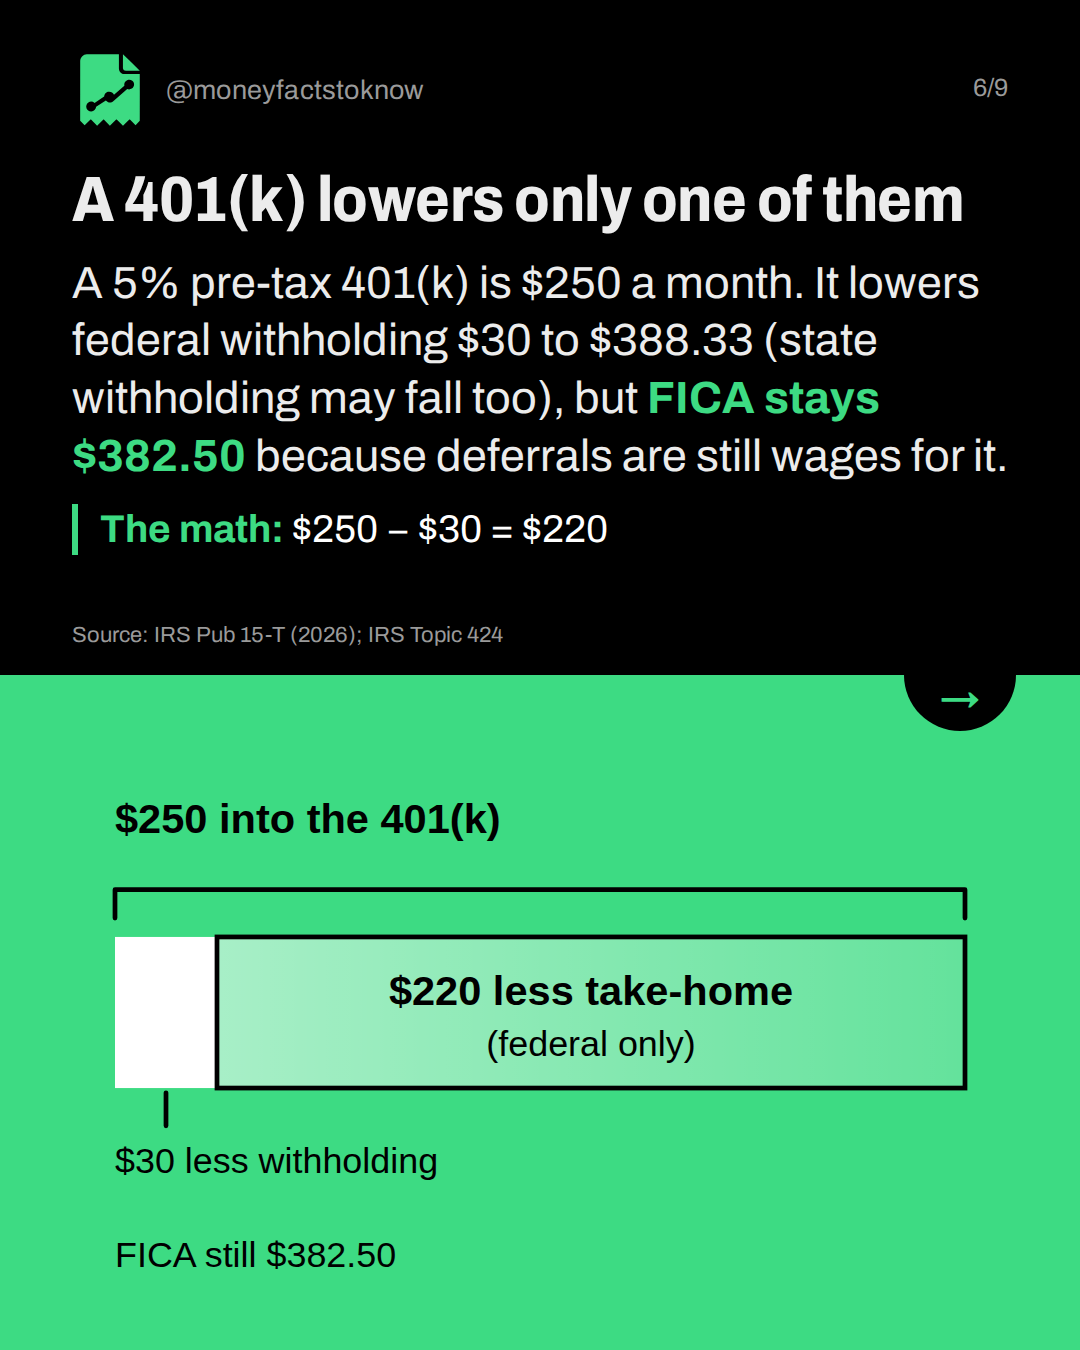
A 401(k) lowers only one of them
A 5% pre-tax 401(k) is $250 a month. It lowers federal withholding $30 to $388.33 (state withholding may fall too), but FICA stays $382.50 because deferrals are still wages for it.
The math: $250 − $30 = $220
Source: IRS Pub 15-T (2026); IRS Topic 424
When this example stops applying
State and local income tax and benefits vary. In 2026, Social Security stops after $184,500 of wages, and an extra 0.9% Medicare is withheld over $200,000. A different W-4 or pay frequency changes withholding.
Source: IRS Topic 751; IRS Pub 15-T (2026)
Match your own pay stub
Find gross pay on your stub, then the Social Security and Medicare lines. They're usually 6.2% and 1.45% of your Social Security/Medicare wages, which can be below gross if health premiums or an FSA/HSA come out pre-tax.
Source: IRS Topic 751, tax year 2026; IRS Pub 15-B (cafeteria plans)
Sources and assumptions
- IRS Topic no. 751, Social Security and Medicare withholding rates: Employee Social Security 6.2%, Medicare 1.45%; 2026 Social Security wage base $184,500; Medicare has no wage base; Additional Medicare Tax of 0.9% withheld on wages over $200,000 (checked 2026-10-05)
- IRS Publication 15-T (2026), Federal Income Tax Withholding Methods: 2026 annual percentage method, single/MFS standard withholding table ($19,900–$57,900: $1,240 + 12%) and Worksheet 1A line 1g $8,600 adjustment when Step 2 is not checked (checked 2026-10-05)
- IRS newsroom: tax inflation adjustments for tax year 2026 (Rev. Proc. 2025-32): 2026 single standard deduction $16,100; single brackets 10% up to $12,400, 12% over $12,400, 22% over $50,400 (checked 2026-10-05)
- IRS Topic no. 424, 401(k) plans: Elective deferrals generally aren't subject to income tax withholding at the time of deferral but are included as wages subject to Social Security and Medicare withholding (checked 2026-10-05)
- IRS Publication 15-B (2026), Employer's Tax Guide to Fringe Benefits: Table 2-1 lists cafeteria plans as Exempt from income tax withholding, Social Security and Medicare, and FUTA for qualified benefits. Accident and health benefits: "Exempt". HSAs: "Exempt for qualified individuals up to the HSA contribution limits". Dependent care: "Exempt up to certain limits, $7,500". Transportation: "Exempt up to certain limits". Health FSA contributions are limited to $3,400 for plan years beginning in 2026. (checked 2026-10-05)
Assumptions:
- Fictional single filer, $60,000 annual salary, paid monthly (12 equal paychecks of $5,000)
- Tax year 2026, federal only; no state or local income tax shown
- No other income, no dependents, standard deduction; 2020-or-later Form W-4 with nothing entered beyond filing status (Step 2 not checked)
- No pre-tax benefits in the base case; the 401(k) example assumes a 5% traditional pre-tax deferral ($250/month, $3,000/year) and no other changes
- Withholding computed with the IRS Pub 15-T 2026 annual percentage method; actual payroll systems may round differently by a few cents
The short version
- $5,000 gross, and $382.50 goes to FICA
- Federal withholding was $418.33 a month (Pub 15-T method)
- A pre-tax 401(k) lowers only income tax withholding
- Take-home fell $220, not $250 (federal only)