 Money Facts To Know
Claiming Social Security at 62 can shrink the check by 30%
The cut doesn't end at 67
Many people assume 62 is a small haircut, or that the check returns to full size at 67. But the cut stays; only months when SSA withheld checks are added back.
Source: 20 CFR 404.410, 404.412
How the reduction is counted
Born in 1960 or later? Full retirement age is 67. Each early month cuts 5/9 of 1% (about 0.56%) for the first 36 months, then 5/12 of 1% (about 0.42%). Age 62 is 60 months early.
Source: 20 CFR 404.409, 404.410
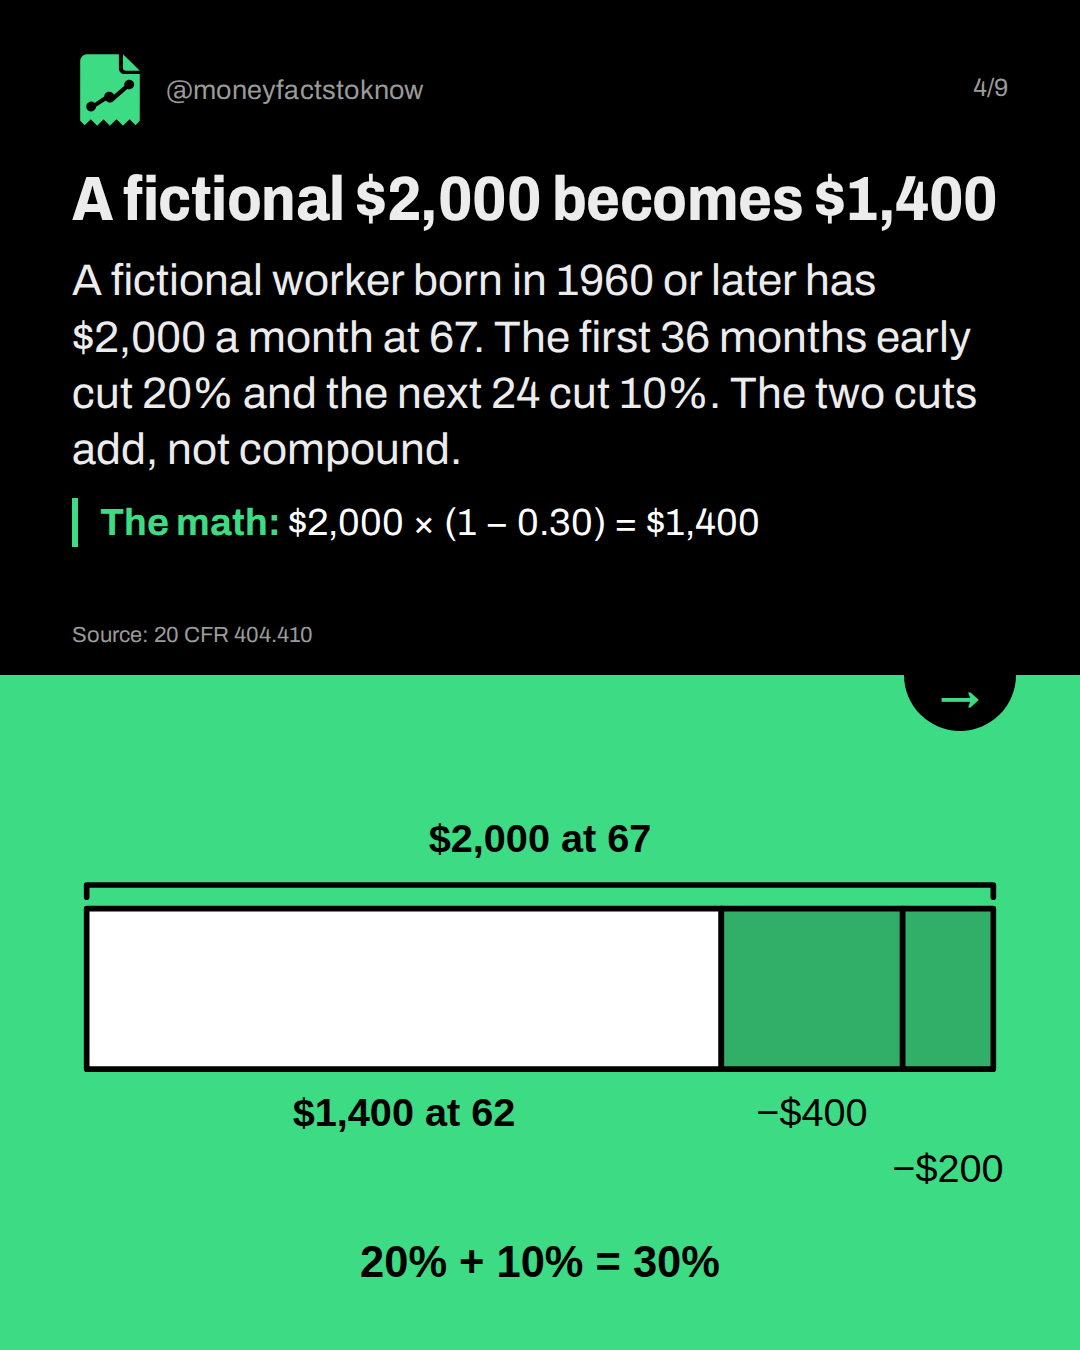
A fictional $2,000 becomes $1,400
A fictional worker born in 1960 or later has $2,000 a month at 67. The first 36 months early cut 20% and the next 24 cut 10%. The two cuts add, not compound.
The math: $2,000 × (1 − 0.30) = $1,400
Source: 20 CFR 404.410
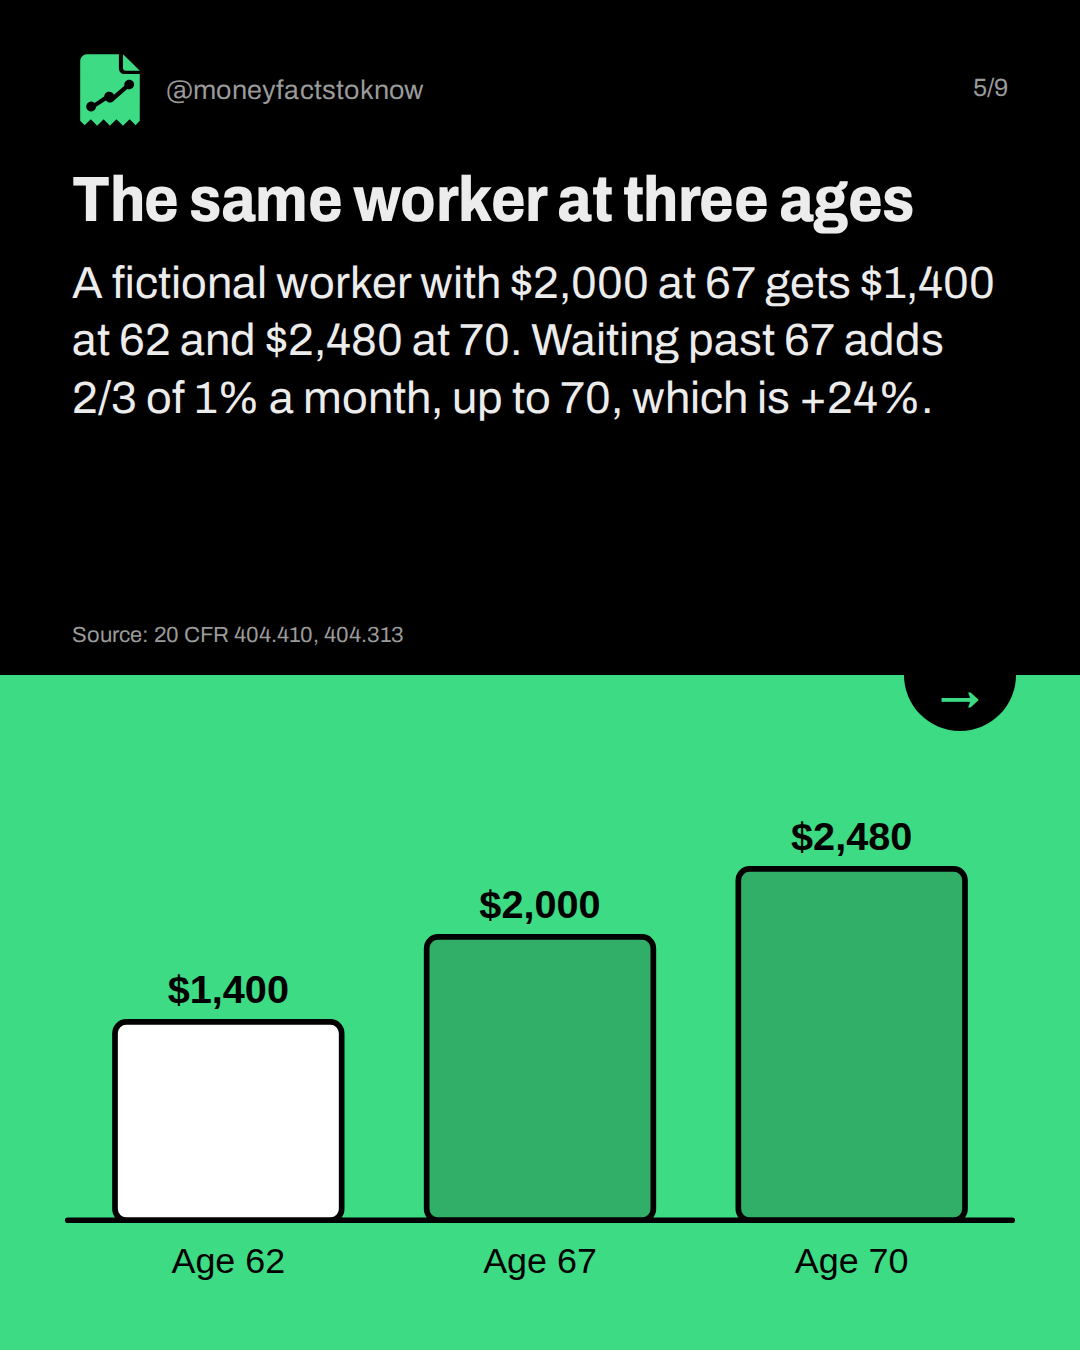
The same worker at three ages
A fictional worker with $2,000 at 67 gets $1,400 at 62 and $2,480 at 70. Waiting past 67 adds 2/3 of 1% a month, up to 70, which is +24%.
Source: 20 CFR 404.410, 404.313
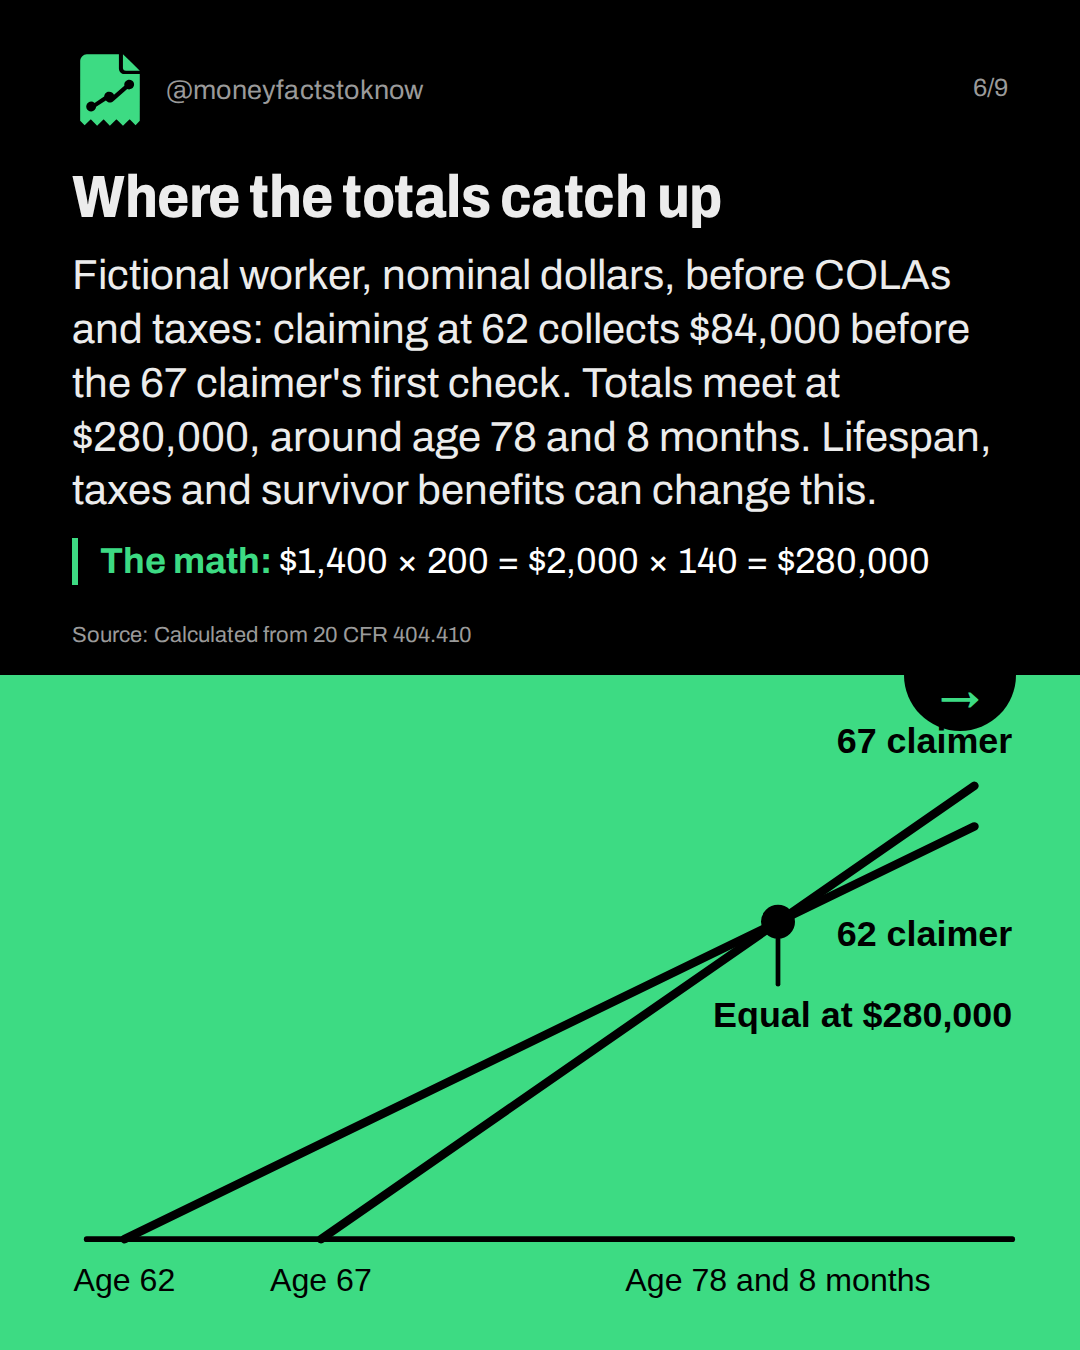
Where the totals catch up
Fictional worker, nominal dollars, before COLAs and taxes: claiming at 62 collects $84,000 before the 67 claimer's first check. Totals meet at $280,000, around age 78 and 8 months. Lifespan, taxes and survivor benefits can change this.
The math: $1,400 × 200 = $2,000 × 140 = $280,000
Source: Calculated from 20 CFR 404.410
When this example stops applying
It changes if you were born before 1960, or if this is a spouse benefit, which is cut 35% at 62. In 2026, working before full retirement age withholds $1 for every $2 above $24,480.
Source: SSA 2026 COLA Fact Sheet, 20 CFR 404.410
Three things to check
Check your birth year, which sets your full retirement age. Compare your SSA estimates at 62, full retirement age and 70, and note whether your earnings will pass the 2026 limit ($24,480 before full retirement age).
Source: 20 CFR 404.409; SSA 2026 COLA Fact Sheet
Sources and assumptions
- 20 CFR 404.409, What is full retirement age? (eCFR text via Cornell LII): Full retirement age is 67 for people born 1/2/1960 and later (a Jan 1, 1960 birthday counts with 1959, full retirement age 66 and 10 months). (checked 2026-10-04)
- 20 CFR 404.410, How does SSA reduce my benefits when my entitlement begins before full retirement age? (eCFR text via Cornell LII): Old-age benefit reduction of 5/9 of 1% for each of the first 36 months and 5/12 of 1% for each month beyond 36. Spouse benefit reduction of 25/36 of 1% for each of the first 36 months and 5/12 of 1% beyond. (checked 2026-10-04)
- 20 CFR 404.412, After my benefits are reduced for age, when and how will I receive benefit increases? (eCFR text via Cornell LII): At full retirement age, SSA recalculates the reduction to leave out months when benefits were withheld (for example under the earnings test). Otherwise the age reduction stays in place. (checked 2026-10-04)
- 20 CFR 404.313, What are delayed retirement credits and how do they increase my old-age benefit amount? (eCFR text via Cornell LII): For people born after Jan 1, 1943, delayed retirement credits are 2/3 of 1% per month (8% a year) from full retirement age through the month they turn 70. (checked 2026-10-04)
- SSA, 2026 Cost-of-Living Adjustment (COLA) Fact Sheet (copy hosted by the American Payroll Association): 2026 retirement earnings test: $24,480/yr under full retirement age, $1 withheld for every $2 above it. Estimated average retired-worker benefit of $2,071/month after the 2.8% COLA, Jan 2026. (checked 2026-10-04)
Assumptions:
- The worker is fictional, born in 1960 or later (but not on Jan 1, 1960), so full retirement age is 67.
- The fictional benefit at full retirement age (primary insurance amount) is $2,000 a month.
- Claiming at 62 means entitlement in the month of turning 62 or later, 60 months before full retirement age. Claiming a month or two after turning 62 means fewer months early and a slightly smaller cut.
- Dollar figures are before SSA's rounding, before COLAs, before Medicare premiums and before income tax.
- The break-even comparison is in nominal dollars, counts no interest on checks received, and assumes the worker has no earnings that trigger the earnings test.
- Claiming at 70 means waiting the full 36 months past 67.
The short version
- Born 1960 or later: 62 means a 30% cut.
- The cut stays after full retirement age.
- A fictional $2,000 becomes $1,400 at 62.
- Waiting to 70 makes it $2,480.
- Check your own SSA estimates first.