 Money Facts To Know
Fictional $30,000 at 7.5%: 72 months, not 48, costs $2,529 more interest
Why a smaller payment costs more
The CFPB (a federal consumer finance agency) says a longer loan may mean smaller payments but more interest. In this example, interest is figured monthly on the balance still owed, and a longer term pays it down slowly.
Source: CFPB, How do I compare auto loan offers?
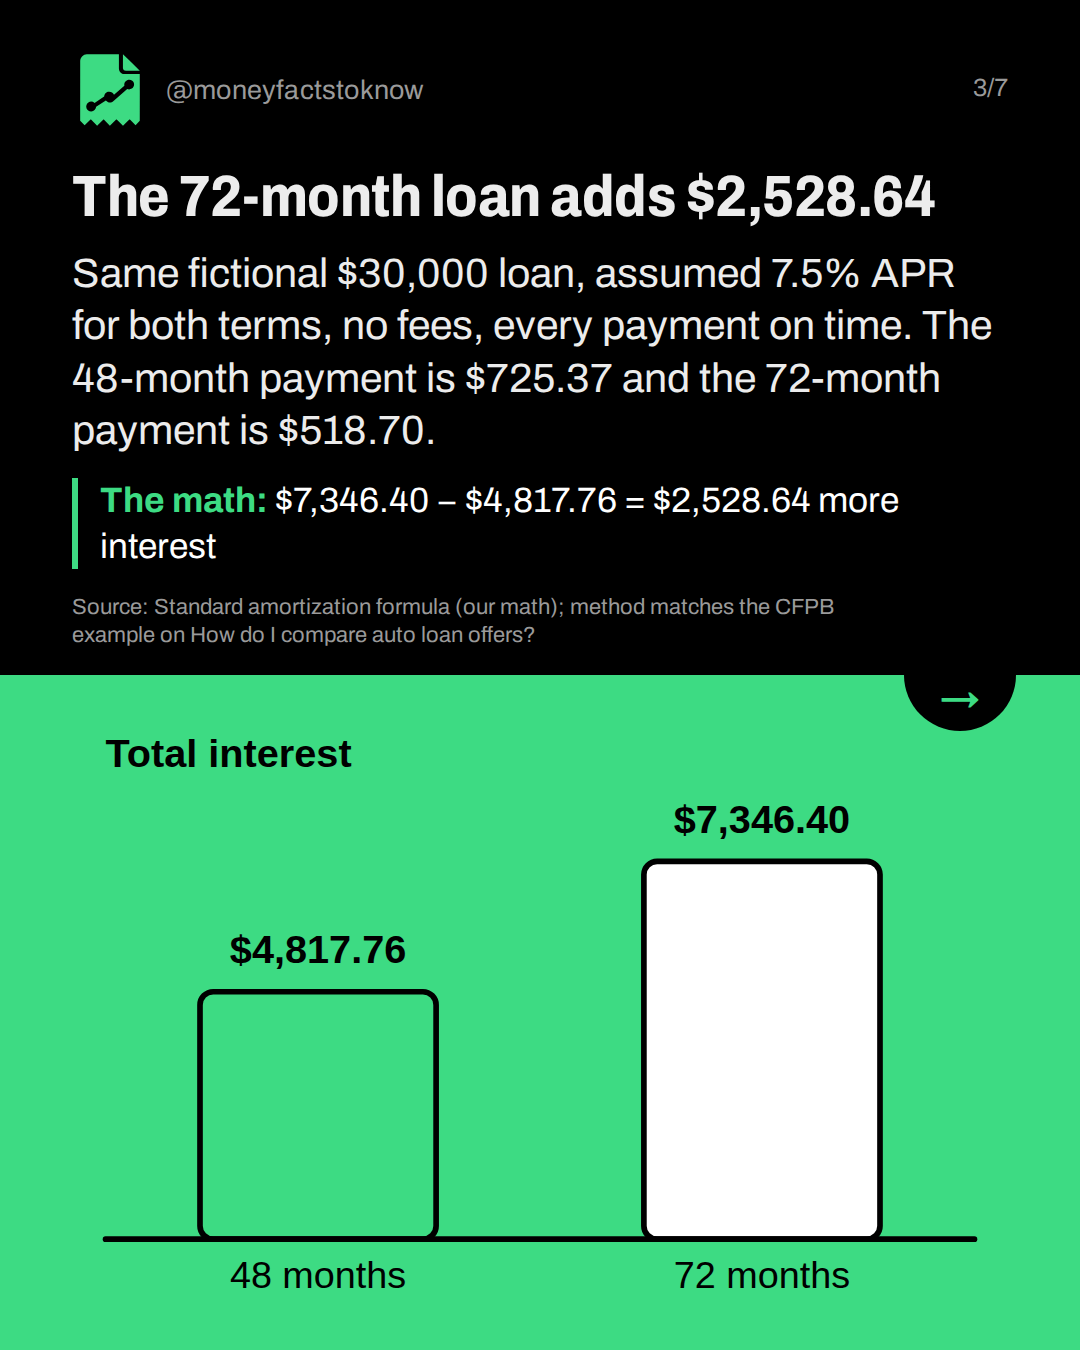
The 72-month loan adds $2,528.64
Same fictional $30,000 loan, assumed 7.5% APR for both terms, no fees, every payment on time. The 48-month payment is $725.37 and the 72-month payment is $518.70.
The math: $7,346.40 − $4,817.76 = $2,528.64 more interest
Source: Standard amortization formula (our math); method matches the CFPB example on How do I compare auto loan offers?
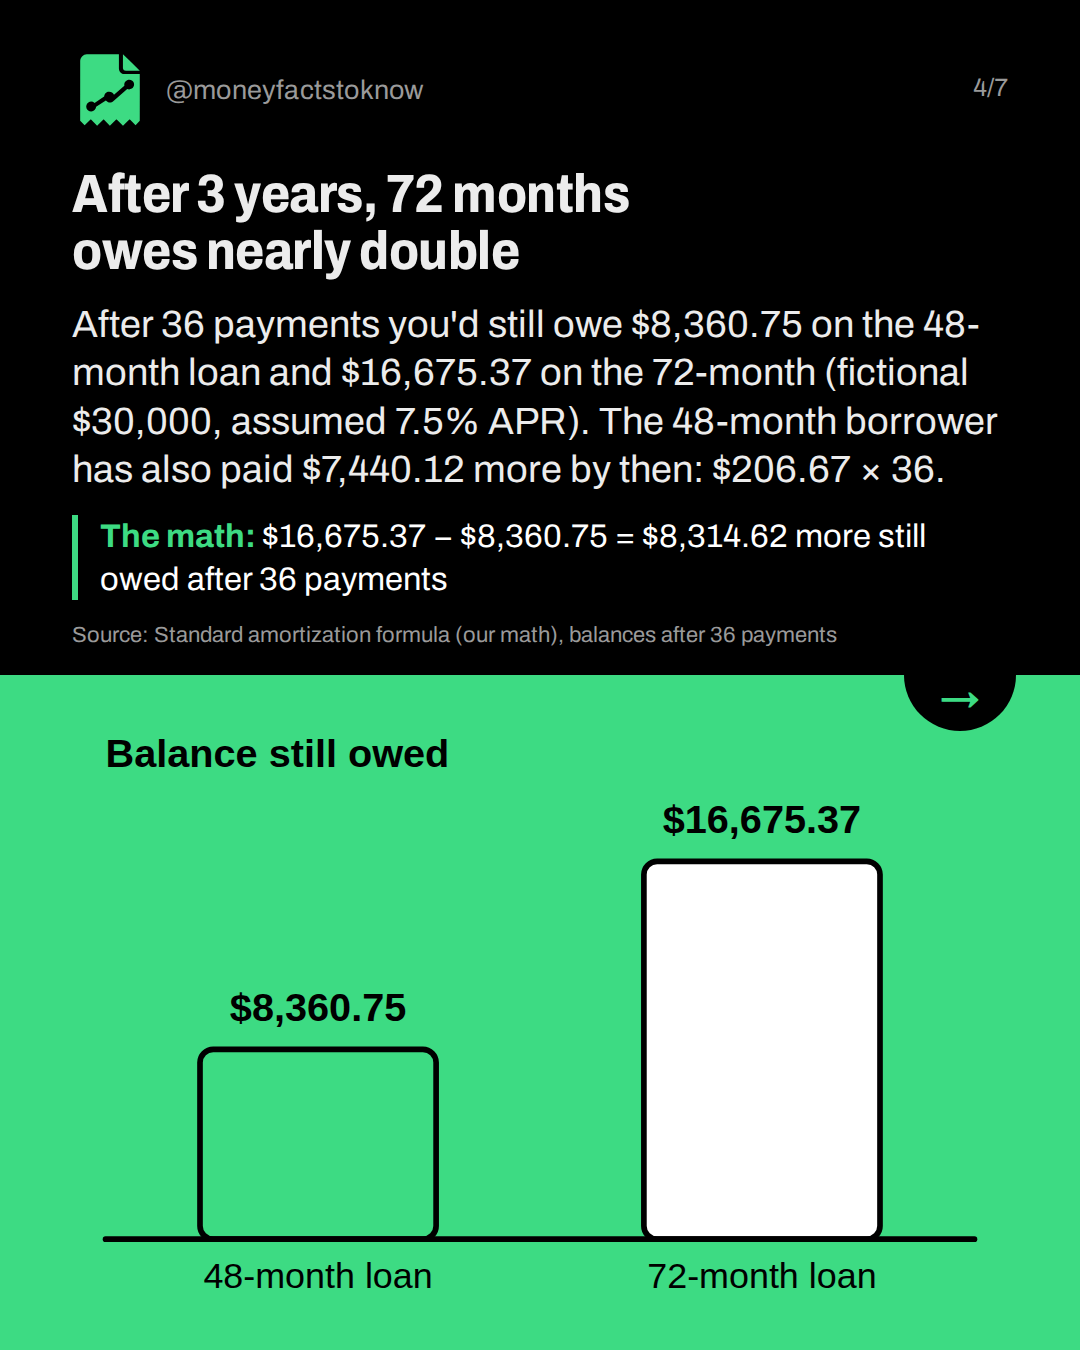
After 3 years, 72 months owes nearly double
After 36 payments you'd still owe $8,360.75 on the 48-month loan and $16,675.37 on the 72-month (fictional $30,000, assumed 7.5% APR). The 48-month borrower has also paid $7,440.12 more by then: $206.67 × 36.
The math: $16,675.37 − $8,360.75 = $8,314.62 more still owed after 36 payments
Source: Standard amortization formula (our math), balances after 36 payments
When this example stops applying
Real rates differ by lender, credit and term. The Fed's August 2026 commercial-bank new-car averages: 7.54% (60-month), 7.17% (72-month), preliminary. No 48-month average is shown. Mandatory fees are included in the APR.
Source: Federal Reserve G.19, Oct 7, 2026 release; CFPB
Check two lines, not one
On the Truth-in-Lending disclosure, compare the finance charge (interest plus certain fees, if every payment is on time) and the total of payments. Ask for it before you sign.
Source: CFPB, Truth-in-Lending disclosure for an auto loan
Sources and assumptions
- CFPB: How do I compare auto loan offers?: A longer term may mean smaller monthly payments but more interest over the life of the loan; the $20,000 at 4.75% example (36 mo $597 / $1,498, 72 mo $320 / $3,024), which our formula reproduces ($597.18 / $1,498.32, $319.78 / $3,024.48); 'Longer loans are more likely to result in your owing more than the vehicle is worth.' (checked 2026-10-26)
- CFPB: What is a Truth-in-Lending disclosure for an auto loan?: Definitions of finance charge, amount financed and total of payments; request the disclosure before signing (checked 2026-10-26)
- Federal Reserve G.19 Consumer Credit release (Oct 7, 2026): Commercial bank new-car loan rates, August 2026 (preliminary): 60-month 7.54%, 72-month 7.17%; 2025 average 72-month 7.80%. Simple unweighted averages of each bank's most common rate. (checked 2026-10-26)
- Congressional Research Service IF13179: The Automobile Loan Market: Policy Issues for Congress (Mar 10, 2026): Average new-car loan term was 69 months in 2025; longer terms lower the monthly cost but raise the total cost; longer maturities may increase negative equity (checked 2026-10-26)
Assumptions:
- Fictional $30,000 amount financed, no down payment or fees in the calculation
- Assumed 7.5% APR, the same for 48, 60, 72 and 84 months (real offers can differ by term and credit)
- Fixed-rate, fully amortizing, monthly payments, 12 periods a year, payments rounded to the cent, every payment made on time, no prepayment
- Balance after 36 payments computed with the rounded payment
- Taxes, title, add-ons and the car's value aren't modeled
The short version
- At the same rate, a longer loan means a smaller payment
- Fictional 7.5% loan, 72 vs 48 months: $2,528.64 more interest
- After 3 years: $16,675.37 owed (72-mo) vs $8,360.75 (48-mo)
- Check finance charge and total of payments


