 Money Facts To Know
Paid late? A penalty APR may not reach your old balance
One late payment, two kinds of balance
Many people assume one late payment lets the card charge its penalty APR, the higher rate in the terms, on everything. Regulation Z treats new purchases differently from the balance already on the card.
Source: CFPB, Regulation Z §1026.55
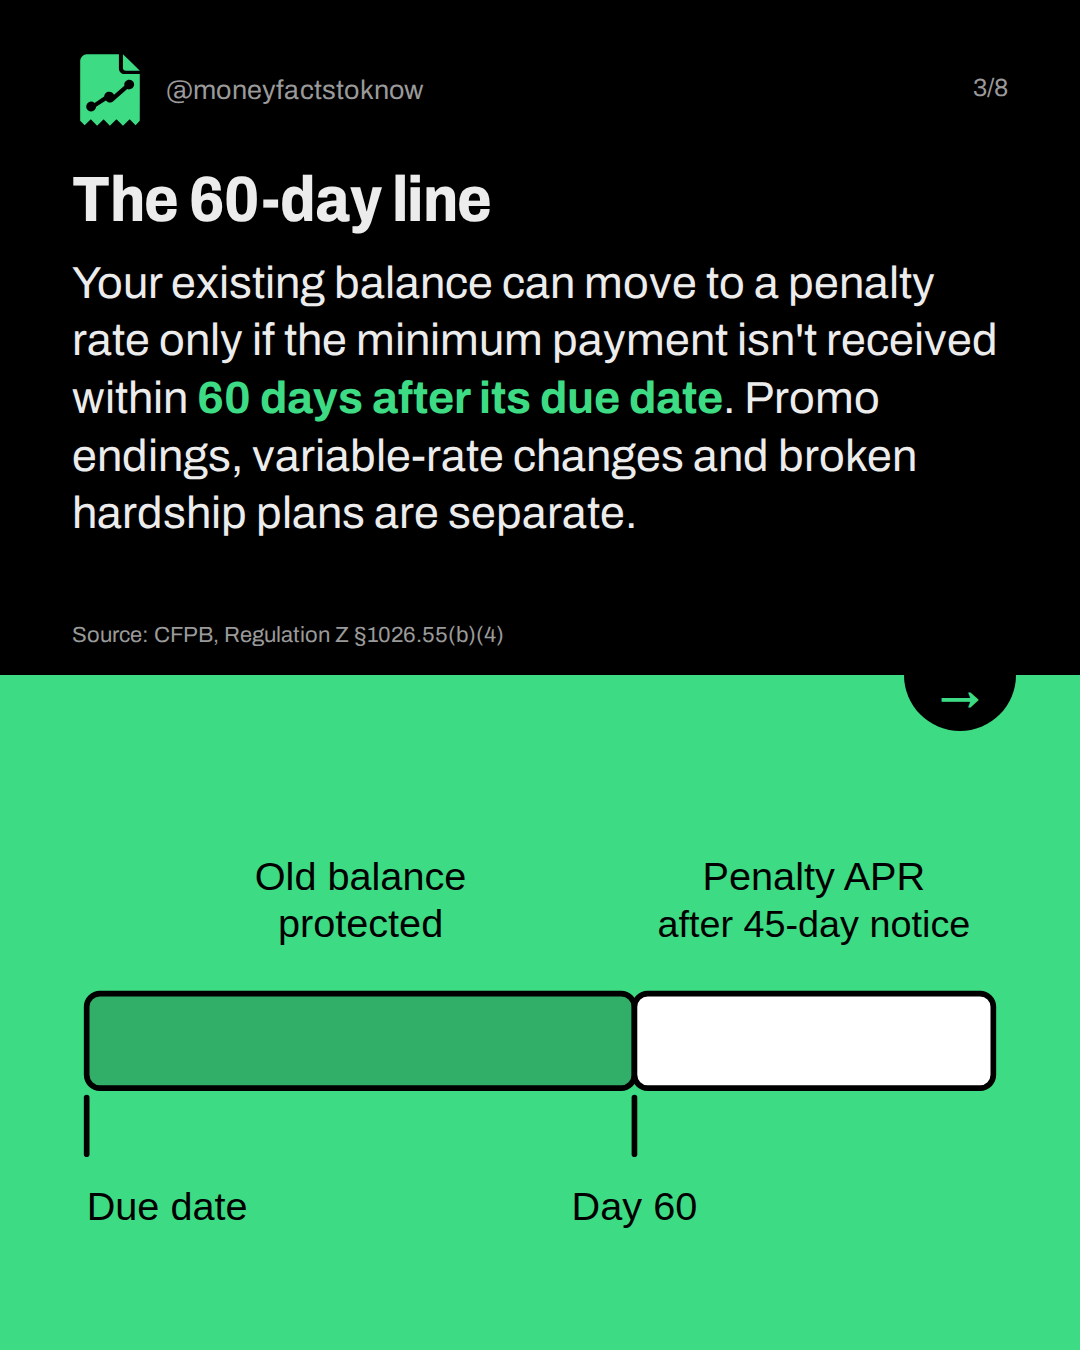
The 60-day line
Your existing balance can move to a penalty rate only if the minimum payment isn't received within 60 days after its due date. Promo endings, variable-rate changes and broken hardship plans are separate.
Source: CFPB, Regulation Z §1026.55(b)(4)
Notice has to come first
A penalty rate needs written notice 45 days ahead; index-driven variable rates and disclosed promo endings don't. After the account's first year, notice can raise rates on new purchases, but not on earlier ones or those within 14 days.
Source: CFPB, Regulation Z §1026.9(c)(2)(v), §1026.9(g) and §1026.55
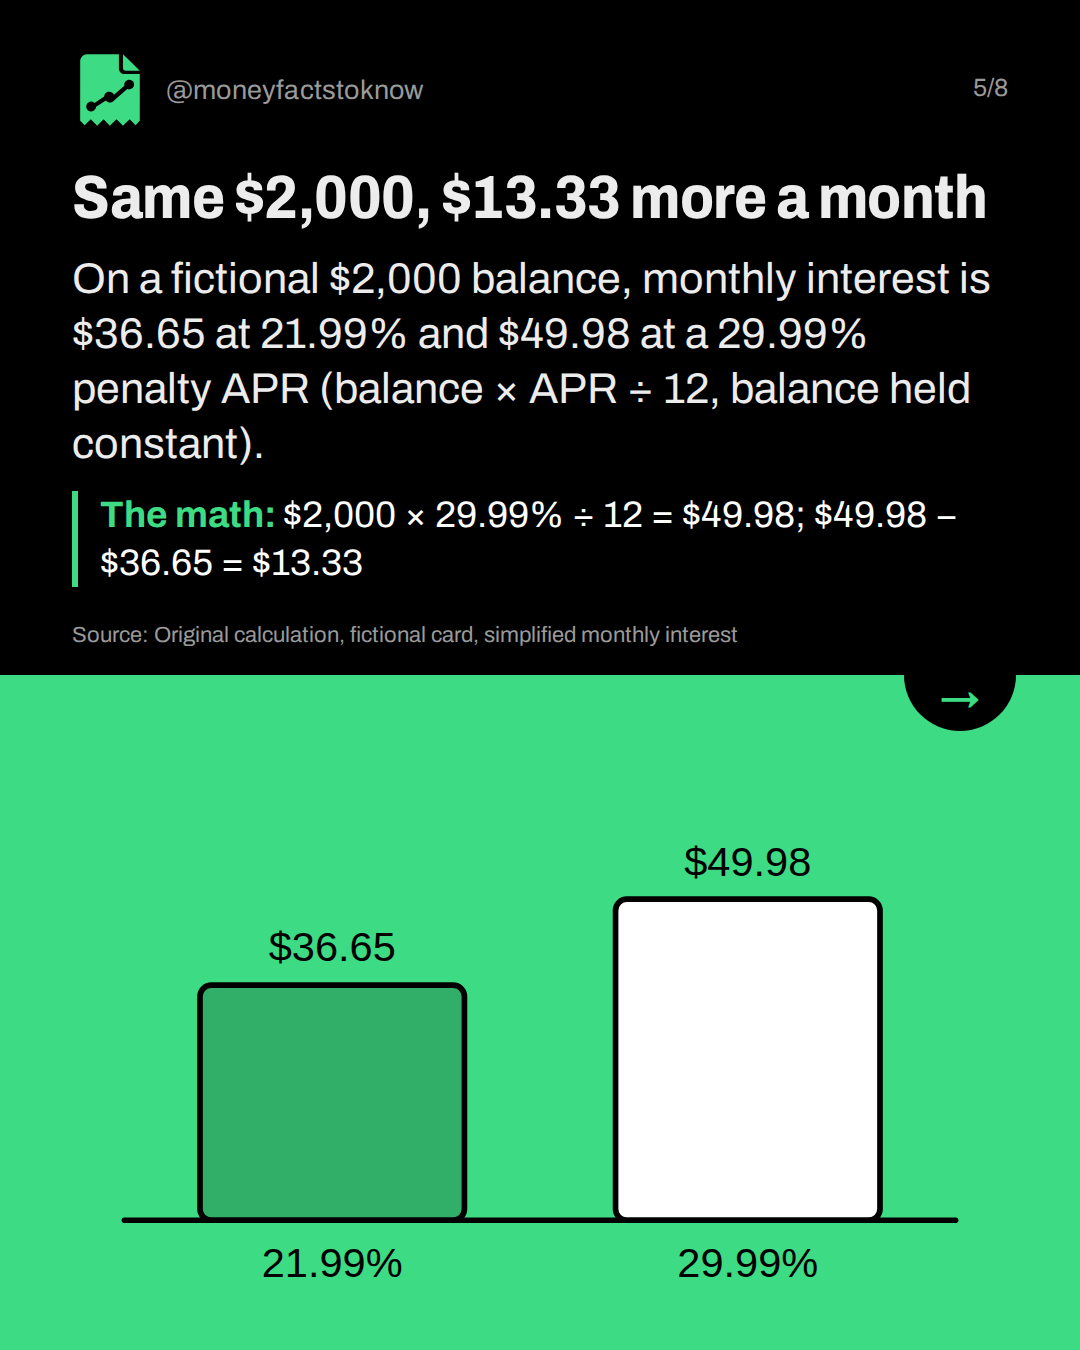
Same $2,000, $13.33 more a month
On a fictional $2,000 balance, monthly interest is $36.65 at 21.99% and $49.98 at a 29.99% penalty APR (balance × APR ÷ 12, balance held constant).
The math: $2,000 × 29.99% ÷ 12 = $49.98; $49.98 − $36.65 = $13.33
Source: Original calculation, fictional card, simplified monthly interest
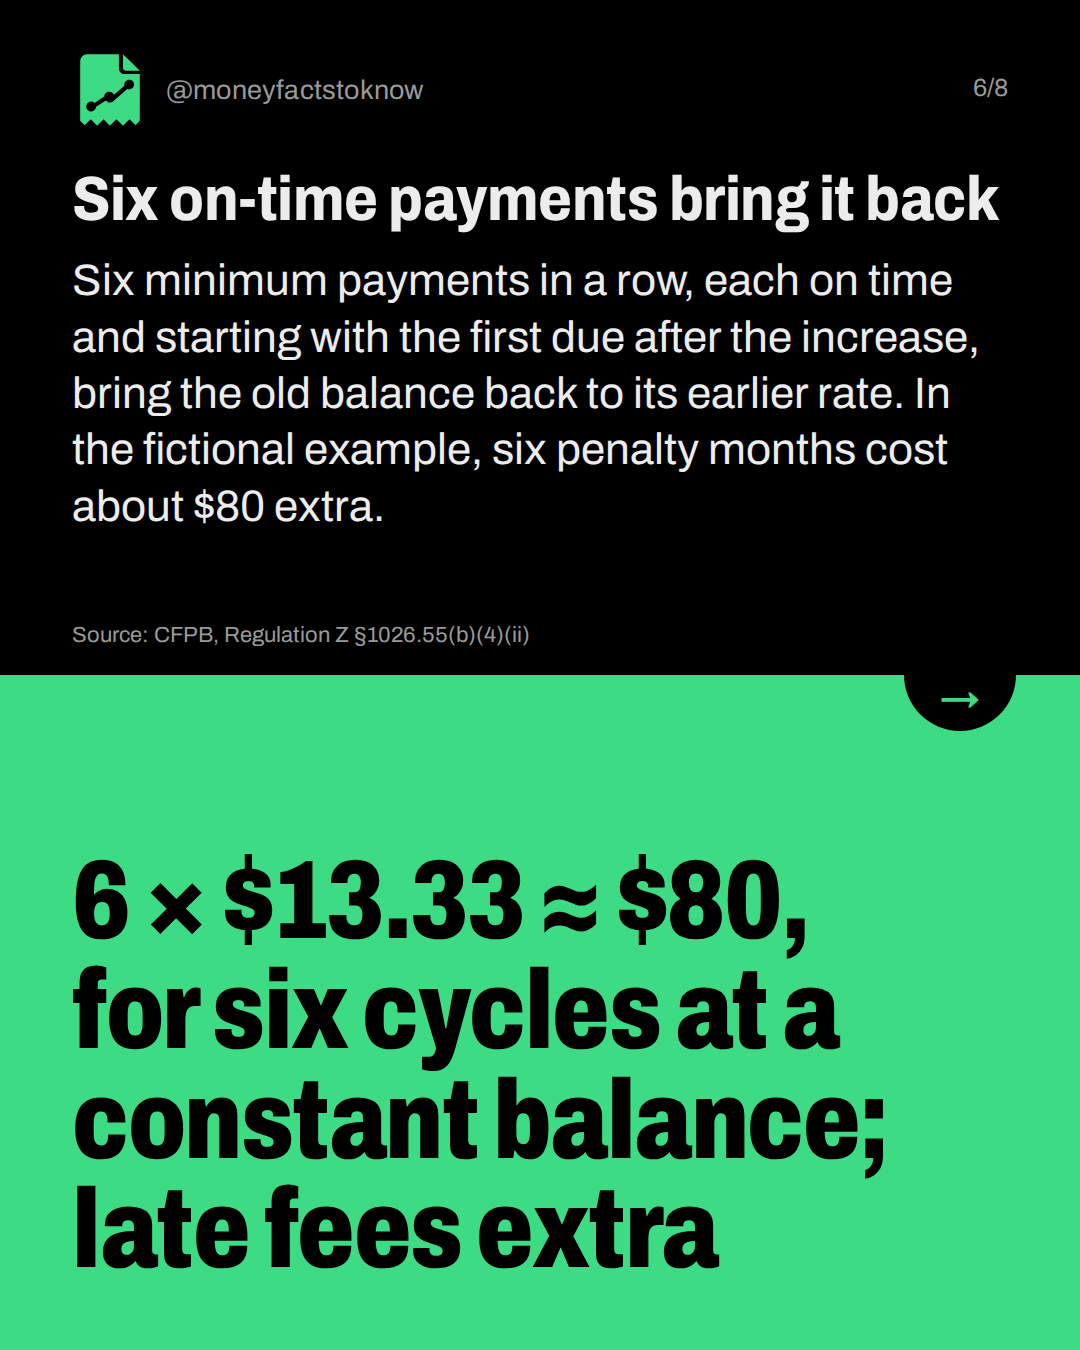
Six on-time payments bring it back
Six minimum payments in a row, each on time and starting with the first due after the increase, bring the old balance back to its earlier rate. In the fictional example, six penalty months cost about $80 extra.
The math: 6 × $13.33 ≈ $80, for six cycles at a constant balance; late fees extra
Source: CFPB, Regulation Z §1026.55(b)(4)(ii)
Check your own agreement
If your card has a penalty APR, it's listed under 'Penalty APR and When it Applies' in your rate table. Promo endings, variable rates and late fees work separately.
Source: CFPB, Regulation Z §1026.60 and §1026.6
Sources and assumptions
- CFPB – Regulation Z §1026.55, Limitations on increasing annual percentage rates, fees, and charges: General ban on card APR increases except listed exceptions; (b)(3) advance-notice exception and its first-year restriction; (b)(3)(ii) an increased rate can't apply to transactions made before or within 14 days after the notice; (b)(4) delinquency exception when the minimum payment is not received within 60 days after the due date; (b)(4)(i) notice must state the reason and the six-payment cure; (b)(4)(ii) six consecutive on-time minimum payments, starting with the first due after the increase, require the issuer to return transactions made before or within 14 days of the notice to the prior rate (checked 2026-10-17)
- CFPB – Regulation Z §1026.9, Subsequent disclosure requirements: (c)(2) written notice of a significant change in terms at least 45 days before the effective date; (g) penalty rate increases need written notice at least 45 days before the effective date (checked 2026-10-17)
- CFPB – When can my credit card company increase my interest rate? What can I do to get the rate back down?: Plain-language confirmation: generally no rate increase on new transactions in the first year; 45 days' notice before a rate change; existing-balance increases are limited to exceptions incl. promo expiry, variable-rate index changes, and minimum payment not received within 60 days after the due date; old rate reinstated after six consecutive on-time minimum payments after the increase; issuers review increased rates every six months (checked 2026-10-17)
- CFPB – Regulation Z §1026.60, Credit and charge card applications and solicitations: (b)(1)(iv): 'if a rate may increase as a penalty for one or more events specified in the account agreement, such as a late payment or an extension of credit that exceeds the credit limit, the card issuer must disclose' the increased rate, a brief description of the triggering events and how long the increased rate lasts. (b)(1)(iv)(A) requires the heading 'Penalty APR and When it Applies'. (checked 2026-10-17)
- CFPB – Regulation Z §1026.6, Account-opening disclosures: (b)(1): account-opening disclosures must be given 'in the form of a table with the headings, content, and format substantially similar to any of the applicable tables in G-17 in appendix G'. (b)(2)(i)(D): disclose 'the increased rate that may apply, a brief description of the event or events that may result in the increased rate, and a brief description of how long the increased rate will remain in effect'. (checked 2026-10-17)
Assumptions:
- Fictional card and fictional terms: $2,000 existing balance, 21.99% standard purchase APR, 29.99% penalty APR (real cards vary; a card whose terms include a penalty rate lists it in its rate table under 'Penalty APR and When it Applies')
- Simplified interest convention: monthly interest = balance × APR ÷ 12 on a balance held constant; real issuers compute interest from a daily periodic rate on the average daily balance, so actual figures differ slightly
- The six-month extra cost ($80) assumes the $2,000 stays constant, the penalty rate applies for exactly six billing cycles, and the cure then returns the rate to 21.99%
- Account is past its first year (the first-year restriction on new-purchase rate increases no longer applies)
- Federal rules only (Regulation Z / CARD Act), US consumer credit card accounts not secured by a home; as of October 2026
The short version
- Old balance: penalty APR needs a payment 60+ days late
- A penalty APR needs 45 days' written notice first
- Six on-time payments restore the earlier rate
- Check your card's rate table and notice dates


