 Money Facts To Know
Fictional 6.5% loan: PMI's 80% and 78% lines are 11 payments apart
PMI doesn't vanish at 20% equity
Many owners assume PMI drops off at 20% equity. The law sets two separate lines, and only the later one is automatic. PMI is private mortgage insurance, usually required on conventional loans with under 20% down.
Source: CFPB
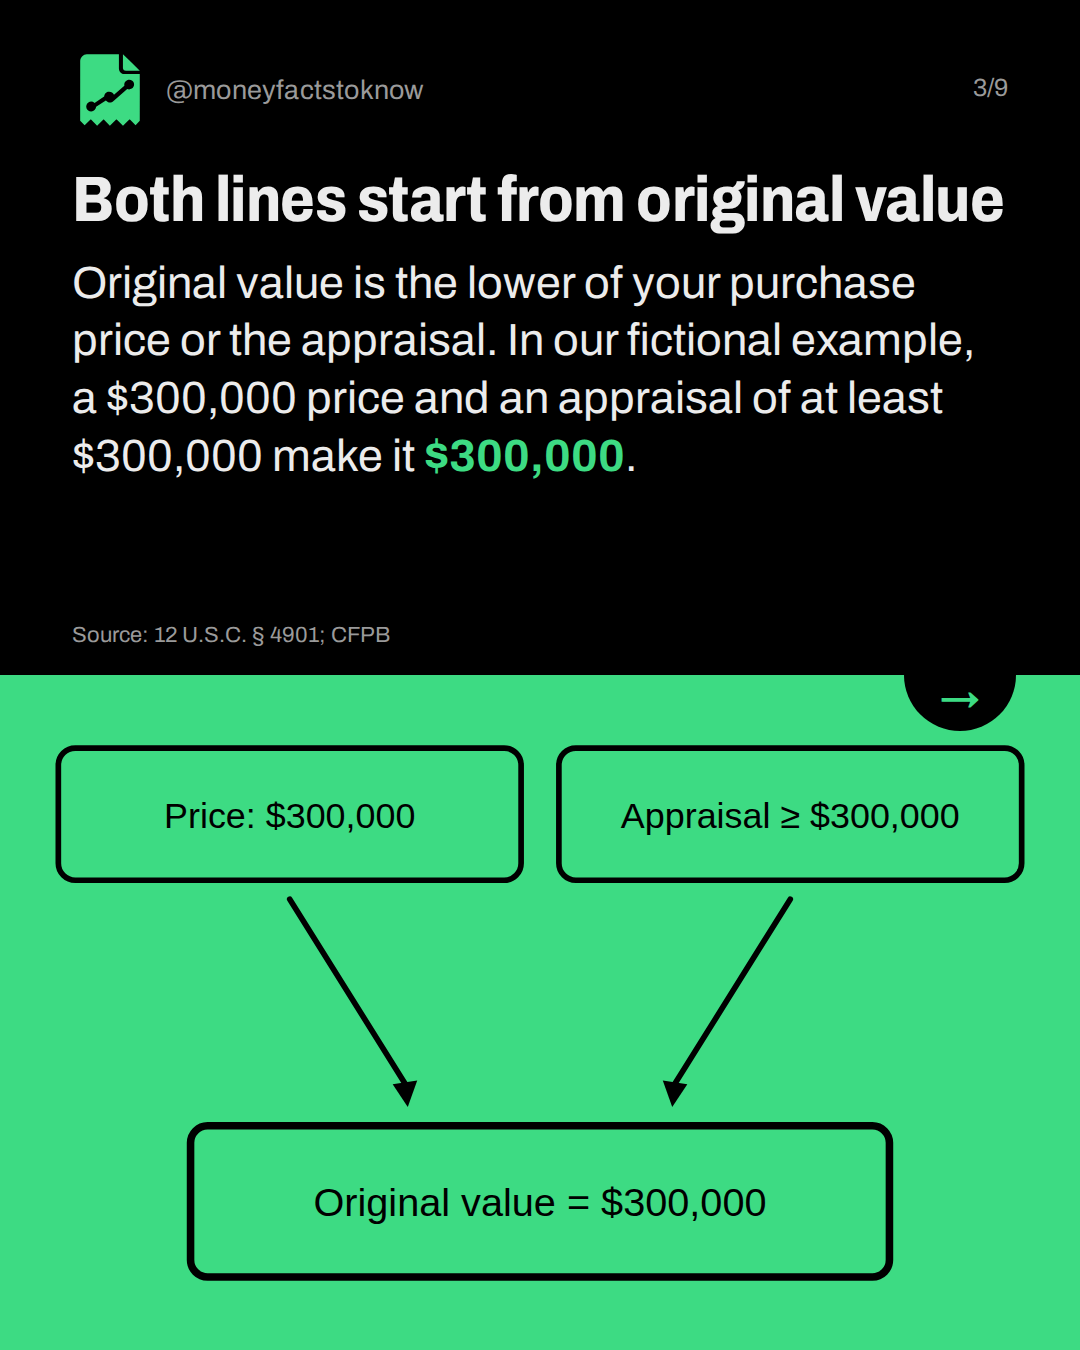
Both lines start from original value
Original value is the lower of your purchase price or the appraisal. In our fictional example, a $300,000 price and an appraisal of at least $300,000 make it $300,000.
Source: 12 U.S.C. § 4901; CFPB
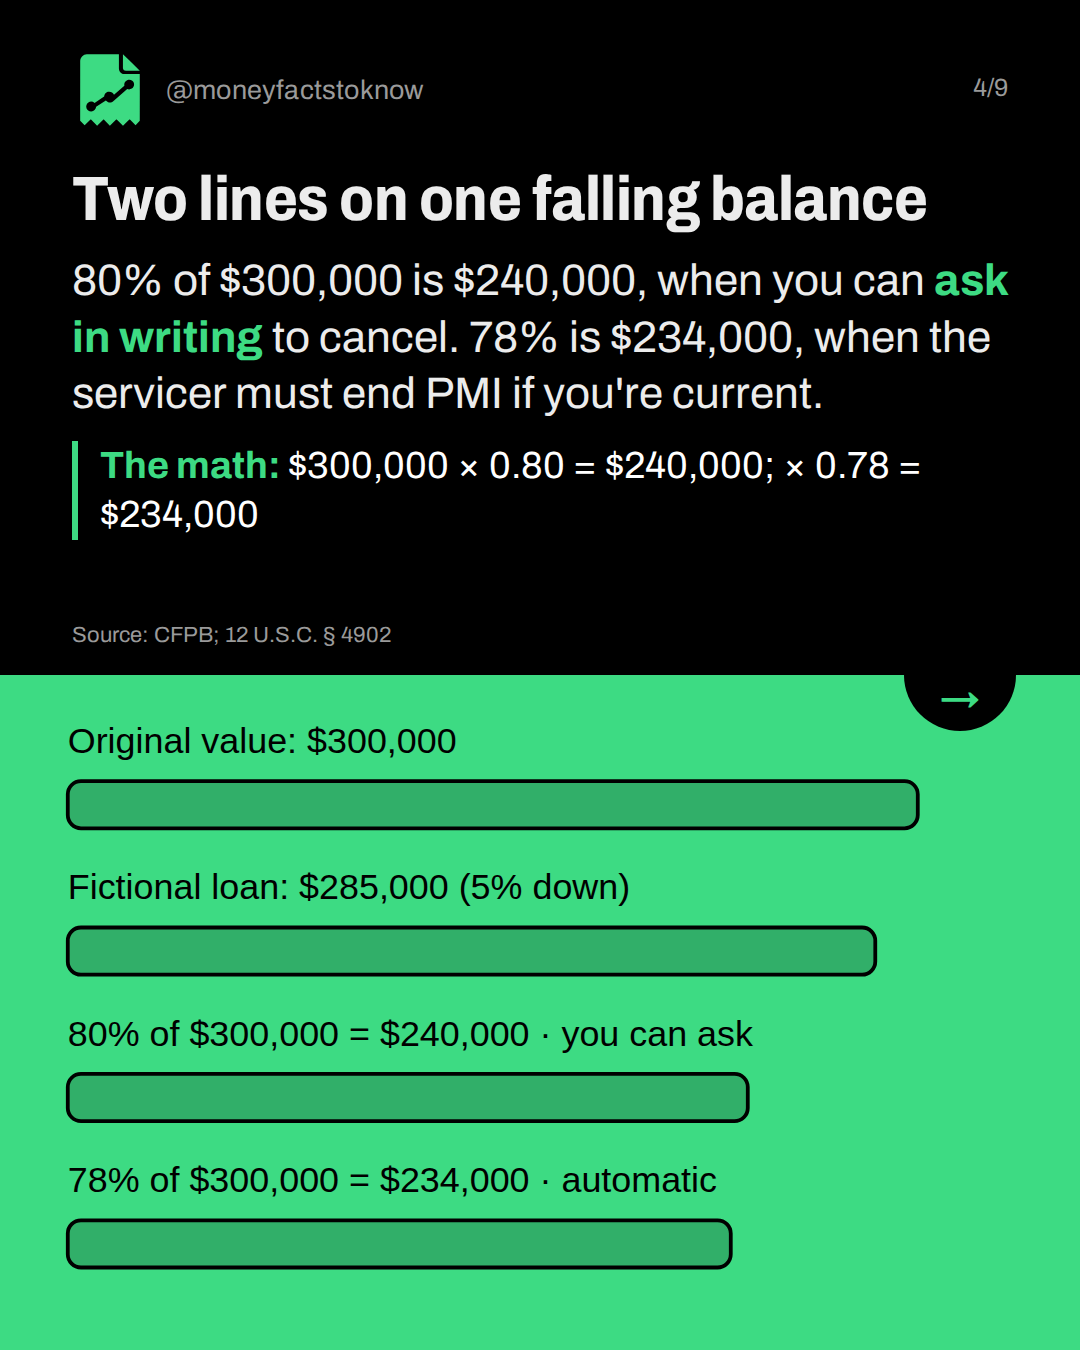
Two lines on one falling balance
80% of $300,000 is $240,000, when you can ask in writing to cancel. 78% is $234,000, when the servicer must end PMI if you're current.
The math: $300,000 × 0.80 = $240,000; × 0.78 = $234,000
Source: CFPB; 12 U.S.C. § 4902
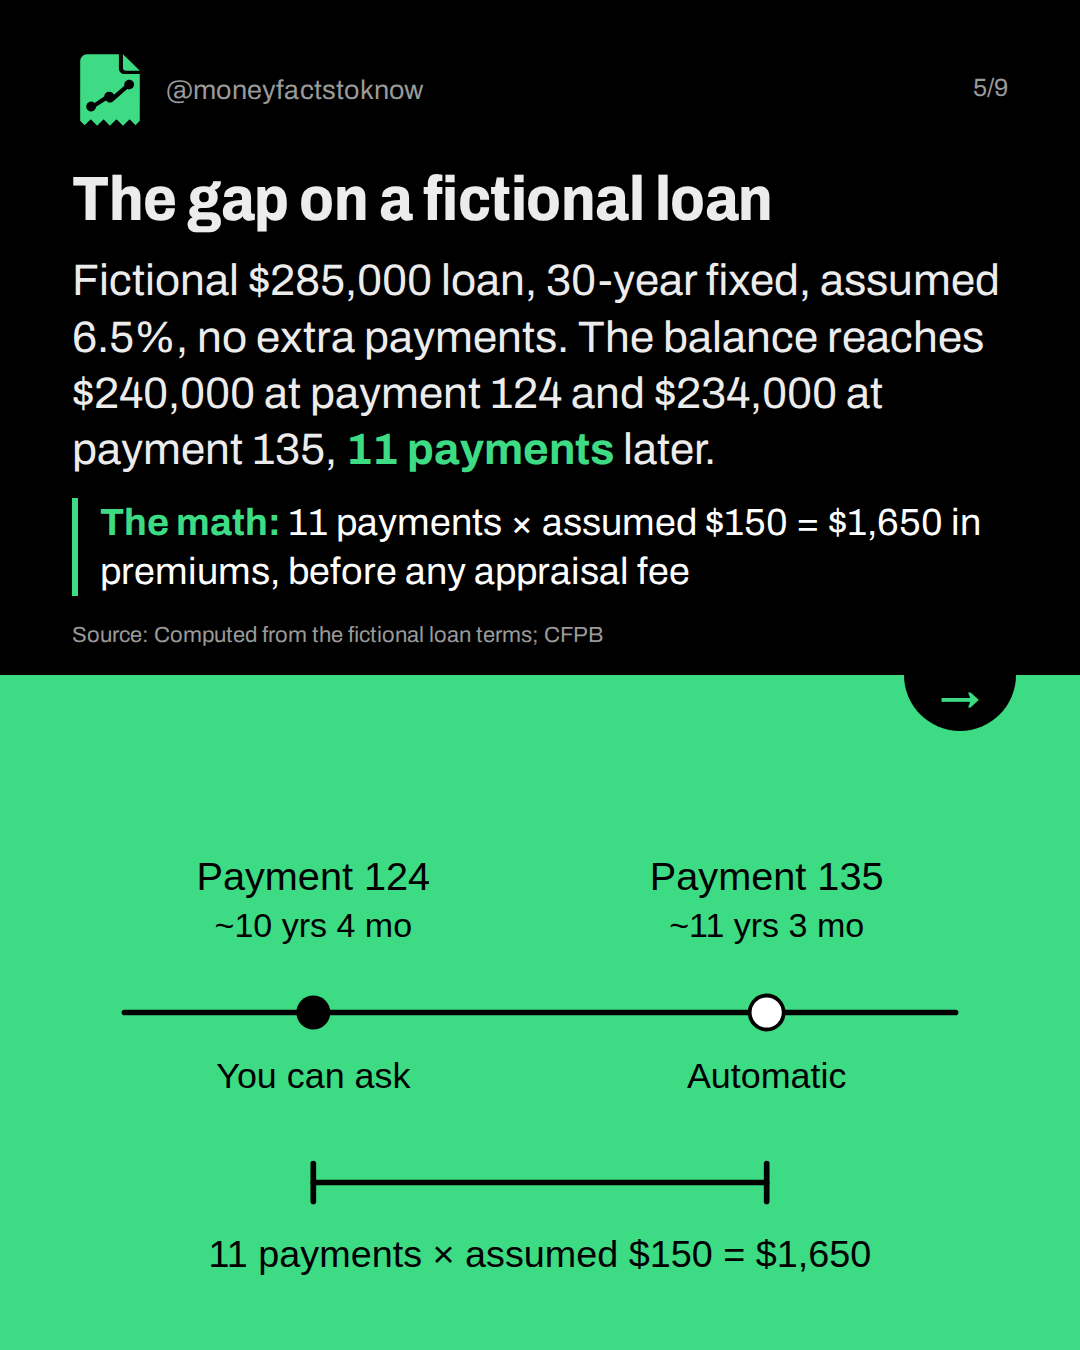
The gap on a fictional loan
Fictional $285,000 loan, 30-year fixed, assumed 6.5%, no extra payments. The balance reaches $240,000 at payment 124 and $234,000 at payment 135, 11 payments later.
The math: 11 payments × assumed $150 = $1,650 in premiums, before any appraisal fee
Source: Computed from the fictional loan terms; CFPB
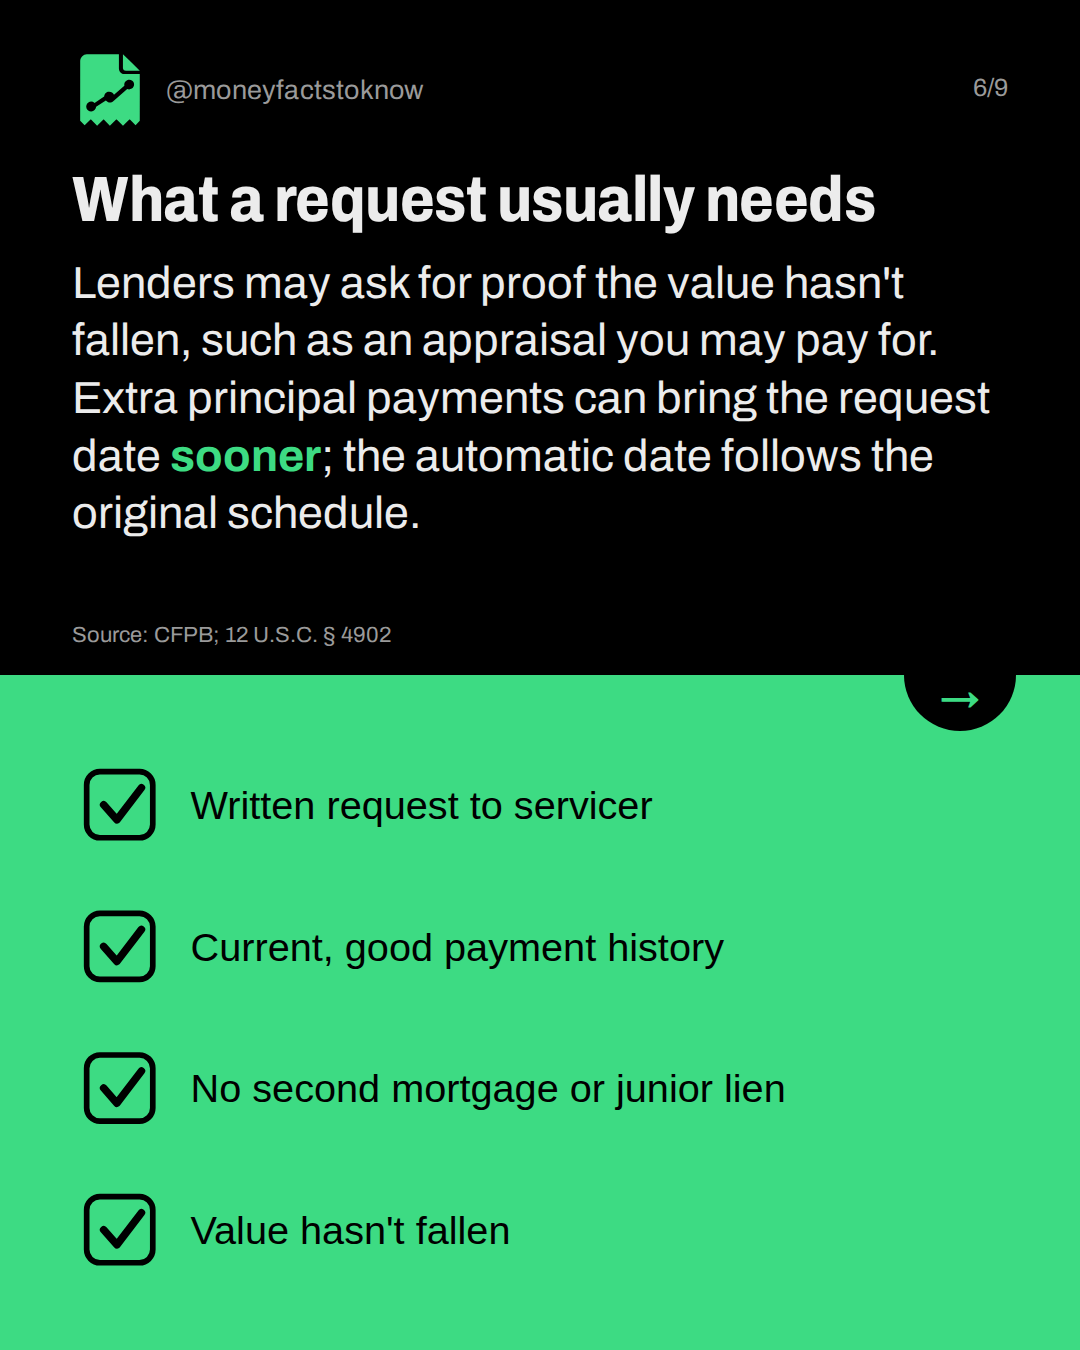
What a request usually needs
Lenders may ask for proof the value hasn't fallen, such as an appraisal you may pay for. Extra principal payments can bring the request date sooner; the automatic date follows the original schedule.
Source: CFPB; 12 U.S.C. § 4902
The backstop and the limits
PMI also ends the month after the loan's midpoint if you're current. Federal rules cover borrower-paid PMI on single-family principal residences closed July 29, 1999 or later; FHA, VA and lender-paid insurance differ.
The math: After a refinance, original value becomes the refinance appraisal.
Source: CFPB; 12 U.S.C. §§ 4901–4902
What to check on your loan
Check your PMI disclosure for the first date you can ask, and compare your balance with 80% of original value. Investors like Fannie Mae and Freddie Mac, or state law, may be more generous. Ask your servicer.
Source: CFPB
Sources and assumptions
- CFPB: When can I remove private mortgage insurance (PMI) from my loan?: 80% request rule with a written request, good payment history and current payments, no junior liens, value not declined; 78% automatic termination if current; final termination the month after the amortization midpoint (15 years on a 30-year loan); original value = lower of the contract sales price or appraised value; refinance uses the refinance appraisal; extra payments let you request early; first request date appears on the PMI disclosure form; FHA/VA have different requirements (checked 2026-10-12)
- 12 U.S. Code § 4901 (Homeowners Protection Act definitions), Cornell LII: Cancellation date = balance first scheduled to reach 80% of original value, or reaches 80% based solely on actual payments; termination date = first scheduled to reach 78%; original value = lesser of contract sales price or appraised value; PMI excludes National Housing Act (FHA), title 38 (VA) and Housing Act of 1949 title V (USDA rural) insurance; covers a single-family principal residence; transactions consummated on or after July 29, 1999; midpoint of amortization period defined (checked 2026-10-12)
- 12 U.S. Code § 4902 (Homeowners Protection Act termination rules), Cornell LII: Borrower cancellation needs a written request, good payment history, current payments, and evidence that the value hasn't declined and equity is unencumbered; automatic termination at the termination date if current (or the first of the month after becoming current); final termination after the midpoint; no premiums more than 30 days after termination; unearned premiums returned within 45 days; high-risk loans are excepted (checked 2026-10-12)
Assumptions:
- Fictional home: $300,000 contract sales price, appraised at or above $300,000, so original value = $300,000
- Fictional loan: $285,000 (5% down), conventional 30-year fixed rate, assumed 6.5% APR used as the note rate, monthly payments, principal and interest $1,801.39 (taxes, insurance and PMI excluded)
- No extra principal payments; the balances are the scheduled amortization balances
- Assumed PMI premium $150 a month, fictional; real premiums vary by lender, credit, and down payment
- Borrower current on payments with good payment history; loan for a single-family principal residence closed after July 29, 1999; not classed high-risk; not FHA/VA/USDA
- Federal law only; a state law or lender policy can be more generous
The short version
- At 80% of original value, you can ask
- At 78%, PMI must end if you're current
- On our fictional home, that's 11 payments apart
- Check your PMI disclosure for the date


