 Money Facts To Know
Fictional single filer, 2026: $8,000 of interest, no federal tax savings
"Write off the interest" isn't automatic
A common belief is that every dollar of mortgage interest lowers your tax. But the IRS lets you deduct it only if you itemize on the itemized-deductions form, Schedule A.
Source: IRS Publication 936 (2025)
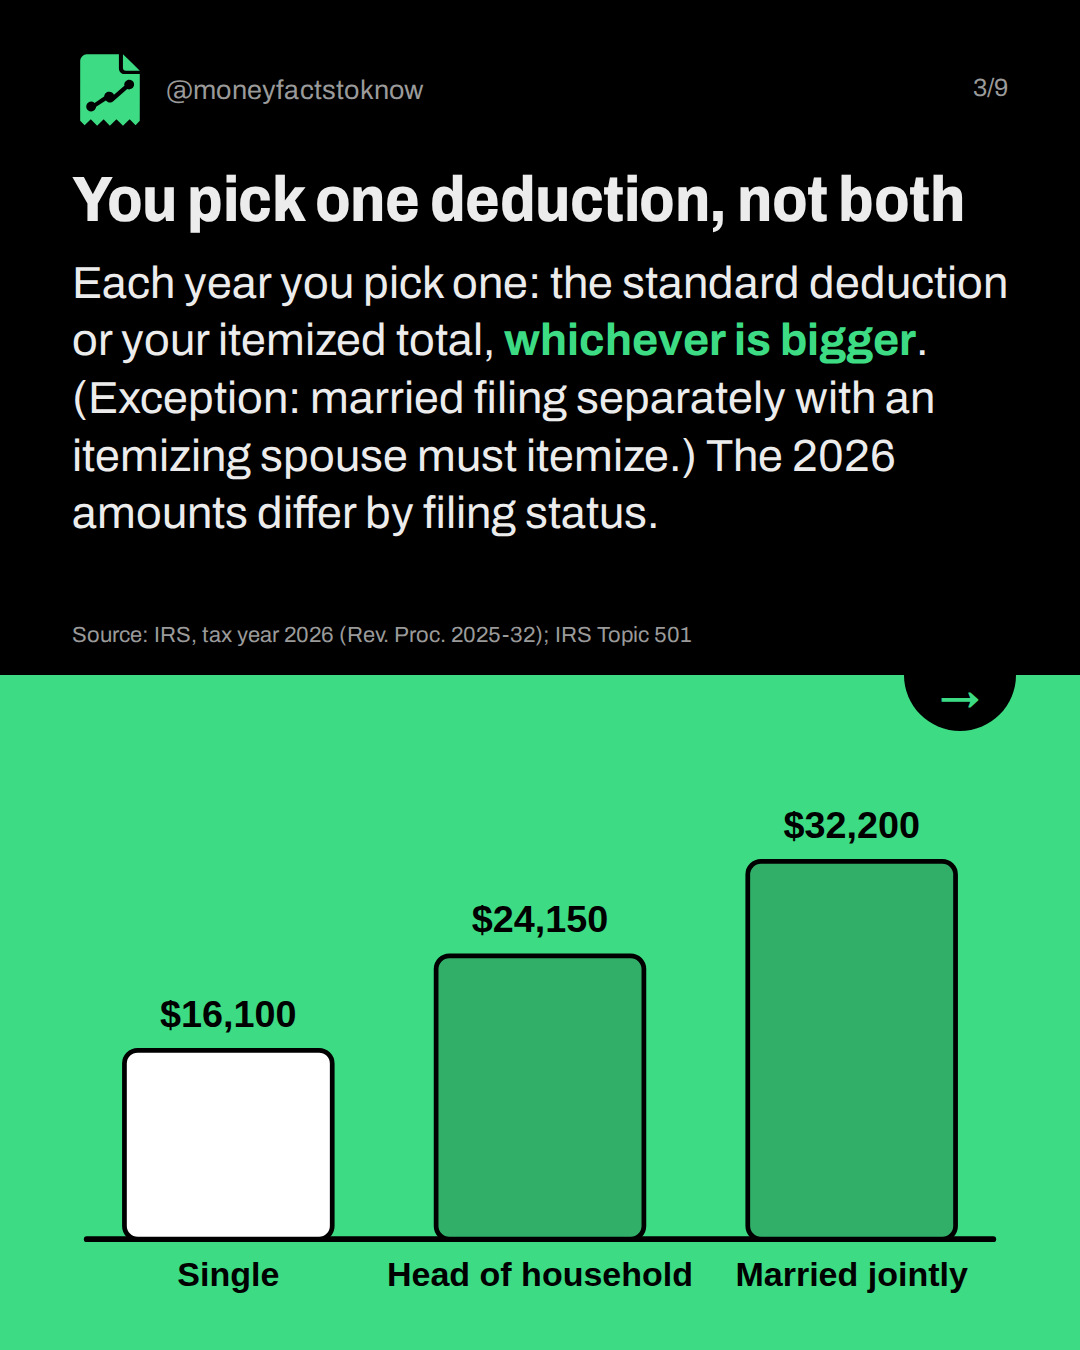
You pick one deduction, not both
Each year you pick one: the standard deduction or your itemized total, whichever is bigger. (Exception: married filing separately with an itemizing spouse must itemize.) The 2026 amounts differ by filing status.
Source: IRS, tax year 2026 (Rev. Proc. 2025-32); IRS Topic 501
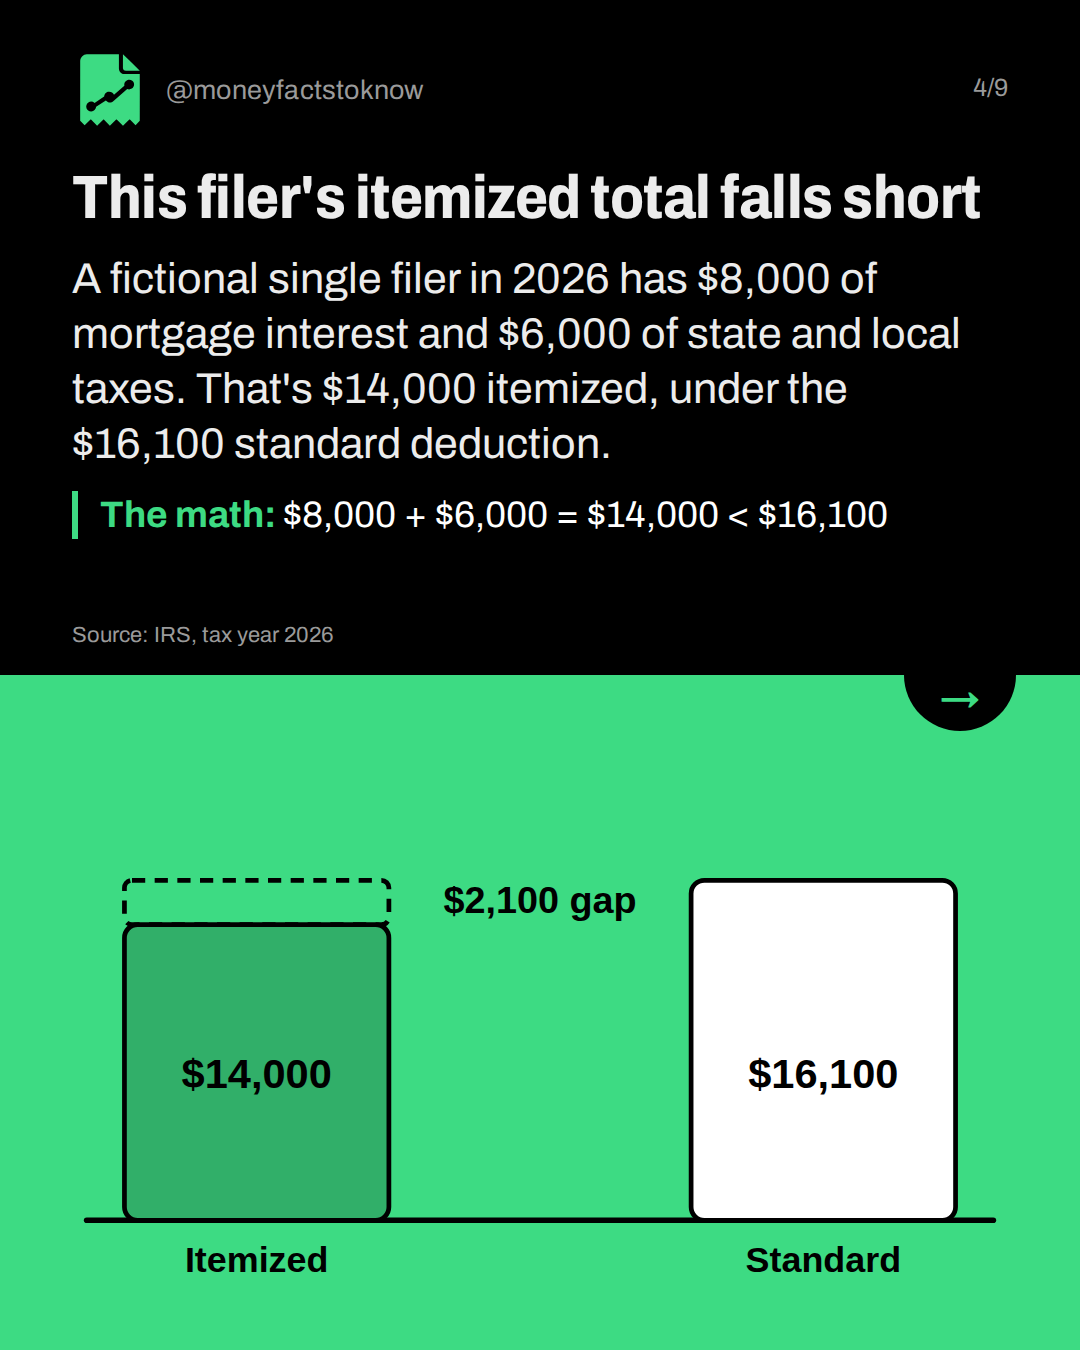
This filer's itemized total falls short
A fictional single filer in 2026 has $8,000 of mortgage interest and $6,000 of state and local taxes. That's $14,000 itemized, under the $16,100 standard deduction.
The math: $8,000 + $6,000 = $14,000 < $16,100
Source: IRS, tax year 2026
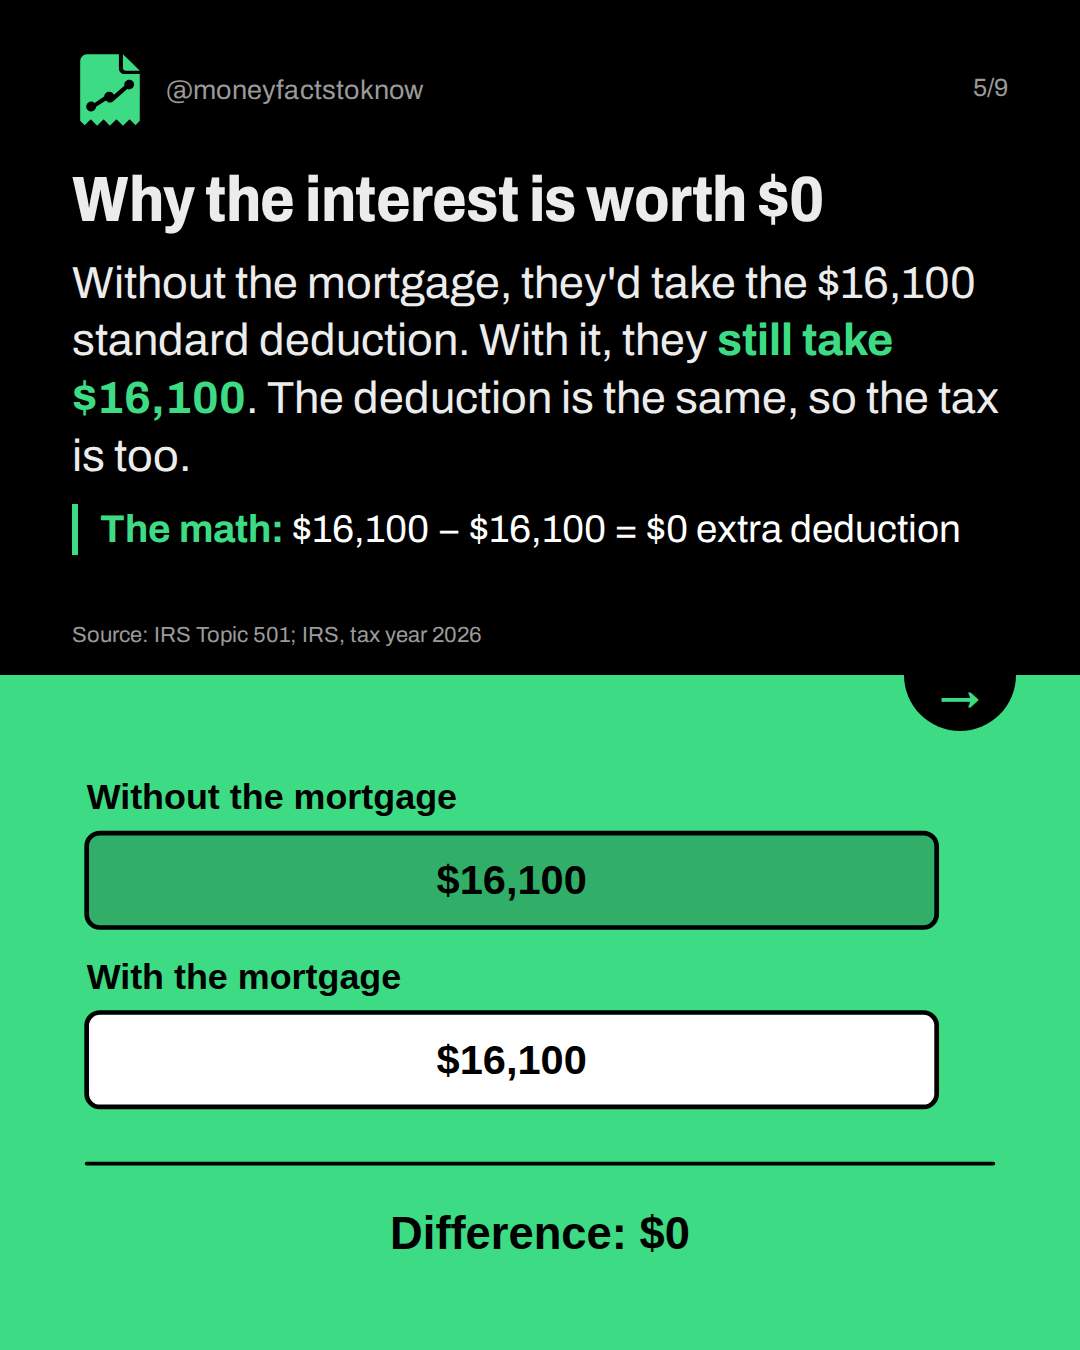
Why the interest is worth $0
Without the mortgage, they'd take the $16,100 standard deduction. With it, they still take $16,100. The deduction is the same, so the tax is too.
The math: $16,100 − $16,100 = $0 extra deduction
Source: IRS Topic 501; IRS, tax year 2026
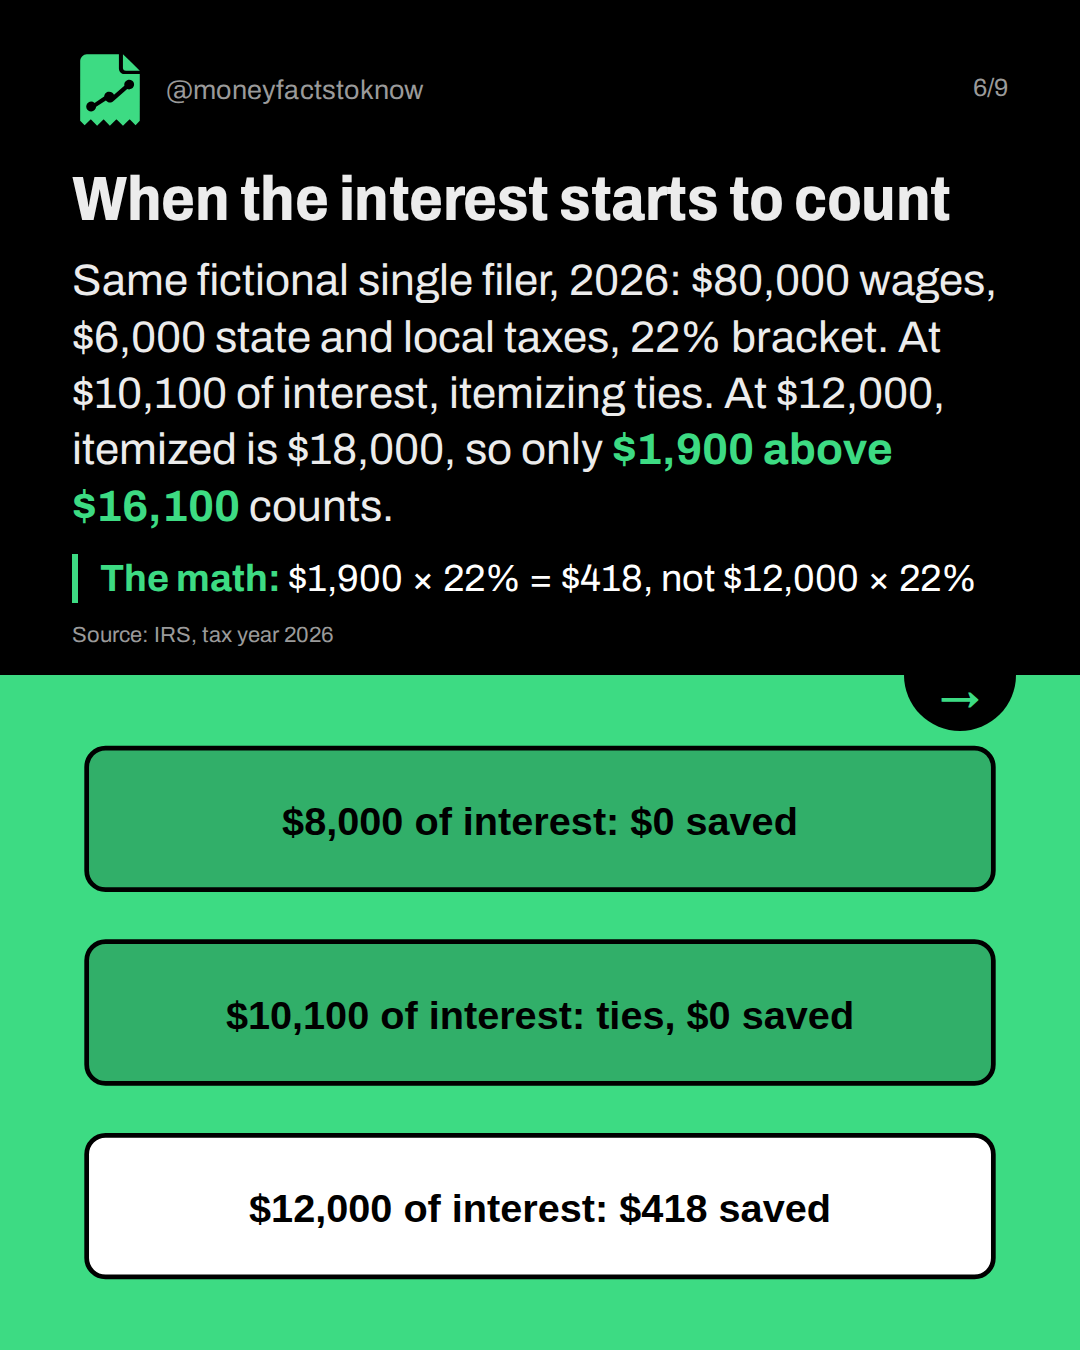
When the interest starts to count
Same fictional single filer, 2026: $80,000 wages, $6,000 state and local taxes, 22% bracket. At $10,100 of interest, itemizing ties. At $12,000, itemized is $18,000, so only $1,900 above $16,100 counts.
The math: $1,900 × 22% = $418, not $12,000 × 22%
Source: IRS, tax year 2026
When this example changes
Numbers differ if you're married ($32,200 joint standard deduction), 65+ or blind, filing separately, or in the 37% bracket. Interest counts on up to $750,000 of acquisition debt ($375,000 separately) for loans after Dec 15, 2017. Federal only.
Source: IRS, tax year 2026; IRS Publication 936
What to check on your own return
Add up all your allowable itemized deductions: mortgage interest, state and local taxes (2026 cap $40,400, lower above $505,000 MAGI), charity and more. Only the amount above your standard deduction lowers taxable income.
The math: Giving cash to charity? Compare against the standard deduction plus up to $1,000.
Source: IRS Topic 501; 26 U.S.C. §164(b)(7); IRS, tax year 2026
Sources and assumptions
- IRS newsroom: IRS releases tax inflation adjustments for tax year 2026 (Rev. Proc. 2025-32, IR-2025-103): 2026 standard deduction $16,100 single/MFS, $32,200 MFJ, $24,150 HoH; 2026 single brackets: 12% over $12,400, 22% over $50,400, 24% over $105,700; limitation on itemized deduction benefit applies only in the 37% bracket (checked 2026-10-10)
- IRS Topic no. 501, Should I itemize?: Itemize 'if the total amount of your allowable itemized deductions is greater than your standard deduction'; you take one or the other (checked 2026-10-10)
- IRS Publication 936 (2025), Home Mortgage Interest Deduction: To deduct mortgage interest you must 'itemize deductions on Schedule A (Form 1040)'; deduction on the first $750,000 ($375,000 MFS) of home acquisition debt; $1 million for debt incurred before Dec 16, 2017 (checked 2026-10-10)
- IRS Topic no. 503, Deductible taxes: SALT deduction (Schedule A lines 5a-5c) limited to a combined $40,000 ($20,000 MFS), subject to a MAGI limitation, not reduced below $10,000 (checked 2026-10-10)
- 26 U.S. Code §164(b)(7) (Cornell LII): Applicable SALT limitation $40,000 for 2025 and $40,400 for 2026; threshold $500,000 (2025) and $505,000 (2026); reduced by 30% of MAGI over the threshold, not below $10,000; reverts to $10,000 after 2029 (checked 2026-10-10)
- IRS: One, Big, Beautiful Bill provisions (Working Families Tax Cuts): Beginning with tax year 2026, non-itemizers may deduct up to $1,000 of cash contributions to eligible charities ($2,000 MFJ) (checked 2026-10-10)
Assumptions:
- The filer is fictional: single, tax year 2026, federal income tax only, no state tax effects modeled.
- Itemized deductions are only $8,000 of qualified mortgage interest plus $6,000 of state and local taxes (under the $40,400 2026 cap); no charity, medical or other itemized items.
- The mortgage is acquisition debt well under the $750,000 limit, so all $8,000 of interest is deductible if they itemize.
- For the break-even/$418 slide: $80,000 of wages and no other income or adjustments, so taxable income is $63,900 (standard) or $62,000 (itemizing at $12,000 interest), both inside the 2026 single 22% bracket ($50,400–$105,700).
- The filer doesn't have to itemize (e.g. not married filing separately with a spouse who itemizes) and isn't in the 37% bracket.
- The filer makes no cash gifts to charity (the 2026 non-itemizer charity deduction would apply the same either way).
The short version
- Mortgage interest lowers federal tax only if you itemize.
- Itemizing pays off when your total beats the standard deduction.
- Only the amount above it lowers taxable income.
- Fictional 2026 filer: $8,000 of interest, $0 saved.


